All posts by Vaibhav G. Karve

Vaibhav G. Karve

About Vaibhav G. Karve

SENIOR MANAGER (OPERATIONS)

Manager – Operations. Working since October 2003.

• Senior Manager - Operations. Working since October 2007.

• Handling a team of 17 providing back office support to USA clients

• Experience includes providing accounts and income tax services to individuals, small and mid-sized companies and co-operative societies.

• 3+ years of audit experience with a total 25 years of experience in financial accounting, auditing and taxation

• 20+ years’ experience in BPO industry.

• Holds a Diploma in Co-operation and Accountancy of Maharashtra State

• Master’s degree of Commerce in Advanced Accounting and Audit

• Loves swimming, horse riding and trekking. Actively involved in arranging large group treks and mountaineering.

Medical Practice Bookkeeping: A Guide to Financial Reporting

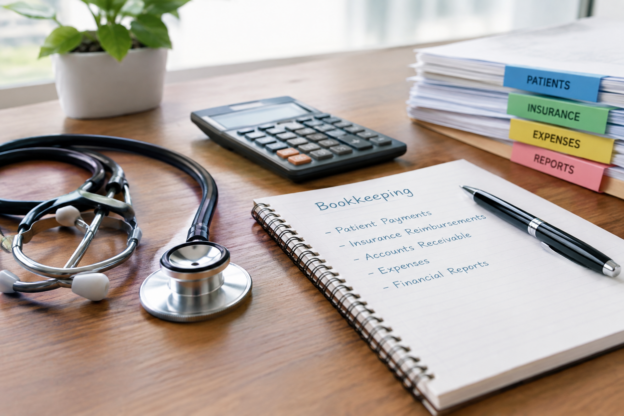
Medical practice bookkeeping workspace

Running a medical practice involves more than providing quality patient care. Healthcare providers must also manage patient payments, insurance reimbursements, payroll, operating expenses, vendor invoices, and financial reporting. Without organized accounting records, understanding a practice’s financial position can become challenging.

Medical practice bookkeeping helps healthcare providers maintain accurate financial records, monitor revenue and expenses, and prepare reliable financial reports. A consistent bookkeeping process also makes it easier to identify outstanding payments, track operating costs, and make informed business decisions.

In this guide, we explain the essential bookkeeping tasks for medical practices, common financial challenges, important financial reports, and how healthcare providers can improve their accounting processes.

Key Takeaways

  • Maintain accurate records of patient payments, insurance reimbursements, and operating expenses.
  • Reconcile bank accounts and payment records regularly.
  • Track accounts receivable to identify outstanding patient and insurance balances.
  • Review financial reports monthly to understand revenue, expenses, and profitability.
  • Protect sensitive financial and patient-related information.
  • Establish clear accounting procedures and reporting deadlines.
  • Consider professional accounting support when internal resources become limited.

What Is Medical Practice Bookkeeping?

Medical practice bookkeeping is the process of recording, organizing, and reviewing the financial transactions associated with a healthcare practice.

These transactions may include patient payments, insurance reimbursements, payroll expenses, medical supplies, rent, equipment costs, and payments to service providers.

Accurate records help practice owners understand how money enters and leaves the business. They also provide the financial information needed to prepare reports, monitor budgets, and support tax preparation.

Common bookkeeping responsibilities include:

  • Recording patient and insurance-related revenue.
  • Tracking accounts receivable and outstanding balances.
  • Recording payroll and employee-related expenses.
  • Processing vendor invoices and payments.
  • Reconciling bank and credit card accounts.
  • Categorizing medical supplies and operating expenses.
  • Preparing monthly financial reports.
  • Maintaining organized accounting documentation.

The specific tasks depend on the size of the practice, its billing arrangements, accounting systems, and internal procedures.

Why Is Bookkeeping Important for Medical Practices?

A reliable bookkeeping process provides healthcare providers with a clearer picture of their financial performance.

1. Better Financial Visibility

Organized financial records help practice owners understand revenue, expenses, and cash flow. This information can support decisions about staffing, equipment purchases, service expansion, and operating budgets.

2. Improved Cash Flow Management

Medical practices may receive payments from patients, insurance companies, and other sources at different times. Monitoring incoming payments and outstanding balances helps practices identify potential cash flow problems earlier.

3. More Accurate Financial Records

Regular transaction reviews and bank reconciliations help identify missing entries, duplicate transactions, and discrepancies between accounting records and bank statements.

4. Better Expense Control

Medical practices incur expenses for supplies, rent, payroll, equipment, software, insurance, and other operating requirements. Categorizing these costs consistently helps owners identify spending patterns and investigate unexpected increases.

5. More Informed Business Decisions

Reliable financial reports help practice owners evaluate operating performance, compare actual results against budgets, and plan for future expenses.

Essential Bookkeeping Tasks for Medical Practices

A consistent accounting workflow helps maintain accurate financial information and reduces the risk of overlooked transactions.

1. Track Patient Payments and Insurance Reimbursements

Medical practices may receive revenue through patient payments, insurance reimbursements, and other healthcare-related arrangements.

These transactions should be recorded accurately and matched with the appropriate billing and payment records.

Where relevant, practices should distinguish between amounts billed, payments received, contractual adjustments, and outstanding balances. This helps prevent confusion between billed revenue and actual cash collections.

Accounting records should also be reconciled with billing-system reports so that discrepancies can be investigated promptly.

2. Manage Accounts Receivable

Accounts receivable represents amounts owed to the practice by patients, insurance companies, or other responsible parties.

Unpaid balances can affect cash flow if they remain unresolved for too long.

Medical practices should regularly review accounts receivable aging reports to identify overdue balances, investigate discrepancies, and coordinate follow-up with the appropriate billing team.

Bookkeeping records should support this process without replacing the practice’s separate clinical billing, claims management, or patient communication procedures.

3. Record Payroll and Employee Expenses

Payroll is often a significant expense for medical practices. Employees may include physicians, nurses, receptionists, medical assistants, and administrative staff.

Maintain accurate records of payroll transactions, employer-related costs, and other employee expenses. Reconcile payroll reports with accounting entries and verify that the amounts recorded match the supporting documentation.

Payroll tax calculations and filings should be handled by the responsible team or qualified provider according to applicable requirements.

4. Monitor Medical Supplies and Operating Costs

Medical practices regularly purchase supplies, equipment, cleaning materials, software, and other resources needed for daily operations.

Organize these transactions into consistent expense categories. Review recurring costs and investigate unusual increases or duplicate invoices.

Major equipment purchases may require different accounting treatment from routine supplies, so they should not automatically be recorded as ordinary operating expenses without reviewing the applicable accounting policy.

5. Reconcile Bank and Credit Card Accounts

Bank reconciliation involves comparing accounting records with bank statements to confirm that transactions have been recorded correctly.

Medical practices should reconcile relevant bank and credit card accounts regularly. The process can help identify missing deposits, duplicate payments, unexpected charges, and recording errors.

Payment processor deposits may include fees or adjustments, so the reconciliation process should account for differences between gross collections and net deposits.

6. Maintain Secure Financial Documentation

Medical practices handle financial information that may be connected to sensitive patient data. Accounting documents should be organized and accessible only to authorized individuals.

Use secure document storage, appropriate user permissions, and established procedures for sharing financial records.

When accounting work involves patient-related information, practices should review applicable privacy and security obligations and ensure that service providers follow the required safeguards.

Important Financial Reports for Medical Practices

Financial reporting helps healthcare providers understand business performance and plan for future needs. Reports should be prepared consistently and reviewed alongside supporting records.

1. Profit and Loss Statement

A profit and loss statement summarizes revenue and expenses over a specific period.

It can help practice owners understand whether revenue is sufficient to cover operating costs and identify categories where expenses may be increasing.

2. Balance Sheet

A balance sheet presents the practice’s assets, liabilities, and equity at a particular date.

It provides information about the practice’s financial position, including cash balances, outstanding receivables, unpaid obligations, and other recorded balances.

3. Cash Flow Report

A cash flow report shows how cash moves into and out of the business.

This report can help practice owners understand whether available cash is sufficient to cover payroll, rent, vendor payments, and other obligations.

4. Accounts Receivable Aging Report

An accounts receivable aging report groups outstanding balances according to how long they have remained unpaid.

It helps the practice identify older balances that may need further review or follow-up.

5. Expense Summary

An expense summary organizes costs by category, such as payroll, rent, supplies, insurance, and software.

Comparing these expenses across months can help identify trends and support budget planning.

Common Bookkeeping Challenges in Medical Practices

Medical practices may face several accounting challenges as transaction volumes and administrative responsibilities increase.

Delayed Insurance Payments

Insurance reimbursement timelines can vary, and differences between billed amounts and collected payments may complicate financial reporting. Regularly reviewing outstanding balances helps practices identify items requiring attention.

Inconsistent Transaction Categorization

Recording similar expenses under different categories can make monthly reports difficult to compare. Establishing consistent accounting rules improves the usefulness of financial information.

Incomplete Reconciliation

When bank accounts, payment processors, payroll records, or billing reports are not reconciled consistently, errors may remain undetected.

Limited Internal Resources

Smaller practices may not have dedicated accounting personnel. Administrative staff may need to balance bookkeeping responsibilities with patient scheduling, billing coordination, and other operational tasks.

Poor Financial Reporting

Delayed or incomplete reports make it harder for practice owners to understand current financial performance. A consistent month-end close process can improve reporting timeliness and accuracy.

In-House vs. Outsourced Bookkeeping

Medical practices can manage bookkeeping internally or engage an external accounting provider. The appropriate approach depends on workload, budget, reporting needs, and available expertise.

Factor In-House Bookkeeping Outsourced Bookkeeping
Staffing Tasks are handled by internal employees Tasks are assigned to an external provider
Oversight Direct internal supervision Requires clear responsibilities and review procedures
Workload Depends on internal staff capacity May provide additional capacity for recurring tasks
Expertise Depends on employees’ experience Depends on the provider’s qualifications and healthcare experience
Cost Includes employee, training, and software costs Depends on the agreed service scope and fees
Data security Managed through internal systems and policies Requires appropriate access controls and contractual safeguards

Outsourcing does not remove the need for internal oversight. Practice owners should understand which tasks the provider handles, which responsibilities remain internal, and how financial information will be reviewed and protected.

How to Improve Bookkeeping and Financial Reporting

Medical practices can strengthen their financial processes through a few practical steps.

  1. Standardize transaction categories: Use consistent categories for revenue, payroll, supplies, and other expenses.
  2. Reconcile accounts regularly: Compare accounting records with bank statements and supporting reports.
  3. Monitor outstanding balances: Review accounts receivable reports and investigate discrepancies.
  4. Set a month-end deadline: Establish a realistic schedule for completing reconciliations and preparing reports.
  5. Use appropriate accounting software: Choose systems that support the practice’s transaction volume and reporting requirements.
  6. Review financial performance monthly: Compare revenue, expenses, and cash flow with previous periods and budgets.
  7. Protect sensitive information: Limit access to financial documents and follow applicable privacy and security requirements.

These practices help create a more consistent financial management process as the practice grows.

How Accountant Anywhere Can Help

Medical practices need organized financial records to understand operating performance, monitor expenses, and make informed decisions.

Accountant Anywhere provides accounting and outsourcing services for businesses, and its website also features information about accounting support for medical clinics. Depending on the services available and the practice’s requirements, professional support may help with recurring bookkeeping, account reconciliations, financial reporting, and other accounting tasks.

Explore the Accountant Anywhere website to learn more about its services. Before engaging a provider, confirm the specific services offered, the team’s experience with medical practices, data-security arrangements, and the responsibilities included in the agreement.

Frequently Asked Questions

1. What does medical practice bookkeeping include?

It may include recording revenue and expenses, tracking accounts receivable, reconciling bank accounts, recording payroll expenses, organizing vendor payments, and preparing financial reports. The exact scope depends on the practice’s needs and accounting arrangements.

2. Why is financial reporting important for medical practices?

Financial reports help practice owners monitor revenue, operating costs, cash flow, outstanding balances, and overall financial performance. Consistent reporting supports budgeting and business planning.

3. How often should medical practices reconcile their accounts?

Many practices reconcile bank and credit card accounts monthly, although higher transaction volumes or internal control requirements may justify more frequent reviews.

4. Which financial reports should a medical practice review monthly?

Common reports include the profit and loss statement, balance sheet, cash flow report, accounts receivable aging report, and expense summary. Practices may also need additional reports based on their billing systems and management requirements.

5. Can bookkeeping be outsourced for a medical practice?

Yes. A practice may outsource selected bookkeeping and accounting tasks if the provider offers appropriate services, follows suitable data-security procedures, and understands the practice’s reporting requirements. Responsibilities should be clearly documented.

6. How can a medical practice improve its bookkeeping accuracy?

Use consistent expense categories, record transactions promptly, reconcile accounts regularly, review supporting documents, and establish a clear month-end closing process.

Conclusion

Accurate financial records are essential for managing the financial side of a healthcare business. Consistent transaction recording, account reconciliation, expense tracking, and monthly reporting help medical practices understand their financial position and identify issues that need attention.

By improving medical practice bookkeeping procedures, healthcare providers can establish more reliable financial records, strengthen reporting, and spend less time resolving avoidable accounting discrepancies.

Whether a practice manages its books internally or works with an external provider, a clear accounting workflow and regular financial reviews can support better business decisions and sustainable operations.

Visit Accountant Anywhere to explore its accounting services and determine whether its available support matches your medical practice’s requirements.
Outsourced Accounting Services for US Small Businesses: What to Evaluate

Accounting professionals discussing financial performance and reviewing income statements

Managing business finances becomes more challenging as a company grows. Business owners must keep accurate books, monitor cash flow, reconcile bank accounts, manage vendor payments, and prepare financial reports while focusing on customers and daily operations. When these responsibilities become difficult to handle internally, outsourcing accounting can be a practical option.

However, choosing an accounting provider requires more than comparing prices. Businesses need to understand which services are included, how financial information is protected, who reviews the records, and whether the provider can support future growth.

When evaluating outsourced accounting services USA, small businesses should focus on service quality, accounting expertise, communication, technology, and transparent pricing. This guide explains the key factors to review before selecting an outsourced accounting partner.

Key Takeaways

  • Define your accounting needs before comparing providers.
  • Confirm exactly which bookkeeping, reporting, payroll, and tax-related services are included.
  • Review the provider’s experience with your business size, industry, and accounting software.
  • Ask how financial data is protected and who can access your records.
  • Compare the total cost of service rather than choosing the lowest quote.
  • Establish clear deadlines, responsibilities, and monthly reporting expectations.
  • Keep ownership of your accounting records and maintain a documented transition plan.

What Are Outsourced Accounting Services?

Outsourced accounting involves hiring an external accounting professional or firm to manage some or all of your business’s accounting activities instead of performing every task internally.

Depending on the agreement, services may include:

  • Daily or monthly bookkeeping
  • Bank and credit card reconciliations
  • Accounts payable and vendor invoice processing
  • Accounts receivable and customer payment tracking
  • Payroll-related accounting entries
  • Monthly financial statements
  • Budget preparation and expense analysis
  • Month-end closing procedures
  • Support for year-end accounting and tax preparation

The exact scope varies between providers. Some firms focus on bookkeeping, while others offer controller-level reporting, financial planning, or coordination with tax professionals.

Before signing an agreement, identify the tasks your business wants to outsource and determine which responsibilities should remain with your internal team.

1. Evaluate the Services Included in the Package

The first step is to understand what the provider will actually do.

The word “accounting” can describe several different activities. A basic bookkeeping package may record transactions and reconcile accounts, while a more comprehensive service may include monthly financial statements, accounts payable, accounts receivable, and management reporting.

Ask potential providers to explain their service scope in writing.

Accounting Function What to Evaluate
Bookkeeping How frequently transactions are recorded and categorized
Bank reconciliation Which accounts are reconciled and how often
Accounts payable Whether invoice entry, approval tracking, and payment scheduling are included
Accounts receivable Whether invoicing, payment tracking, and outstanding balance reports are provided
Financial reporting Whether monthly profit and loss statements, balance sheets, and cash flow reports are included
Payroll accounting Whether payroll journal entries and reconciliations are covered
Month-end close The expected completion date and review process
Tax support Whether tax preparation, filing, or coordination with a tax professional is included

Do not assume that tax filing, payroll administration, or financial advisory services are automatically included.

A written service agreement helps prevent misunderstandings and makes it easier to compare providers on an equal basis.

2. Check Industry Experience and Accounting Expertise

Different businesses have different accounting requirements. A service-based business may have relatively straightforward transactions, while an e-commerce company may need inventory accounting, sales tax tracking, payment processor reconciliation, and more complex revenue reporting.

When evaluating a provider, ask about its experience with businesses similar to yours.

Useful questions include:

  • Have you worked with businesses in my industry?
  • Can you manage multiple bank accounts or business entities?
  • Are you familiar with our accounting software?
  • Who reviews the financial records?
  • What experience does the assigned accounting team have?
  • Can you provide a sample of the monthly reports you deliver?

For specialized accounting requirements, ask whether the provider has the relevant expertise or works with a qualified professional when needed.

You should also distinguish bookkeeping from services requiring specific professional credentials. If you need tax advice, an audit, or another regulated professional service, verify that the person or firm is appropriately qualified to provide it.

3. Review Data Security and Confidentiality

Accounting records contain sensitive business information, including bank transactions, customer details, vendor records, payroll information, and financial performance data.

Before sharing access, understand how the provider protects this information.

Important safeguards to evaluate include:

  • Multi-factor authentication for accounting systems
  • Individual user accounts rather than shared passwords
  • Role-based access permissions
  • Encryption for stored and transmitted information
  • Secure document-sharing procedures
  • Regular access reviews
  • Data backup and recovery procedures
  • Written confidentiality and data-handling agreements
  • A documented process for reporting security incidents

Ask whether the provider can explain its security controls and provide relevant documentation.

If the provider or its team operates outside the United States, clarify where data will be accessed and stored, which subcontractors may be involved, and what contractual protections apply.

Your business should retain appropriate control over its financial systems and ensure that access can be changed or revoked when responsibilities change.

4. Understand the Pricing Structure

Pricing is an important part of the decision, but the cheapest option is not always the most suitable.

Outsourced accounting fees depend on factors such as transaction volume, number of accounts, reporting requirements, business complexity, and the condition of existing financial records.

Providers may charge a fixed monthly fee, a transaction-based fee, an hourly rate, or a combination of these models.

Before accepting a quote, ask whether it includes:

  • Monthly bookkeeping and reconciliations
  • Financial statement preparation
  • Month-end closing
  • Accounts payable and receivable support
  • Software subscriptions
  • Historical bookkeeping cleanup
  • Year-end reporting
  • Tax preparation or filing, if required
  • Additional reporting requests
  • Onboarding and transition costs

Request a written breakdown of included services and potential extra charges.

For example, a low monthly fee may cover transaction entry but exclude reconciliations and financial statement preparation. Another provider may charge more while offering a broader service package.

Compare the total cost against the actual work your business needs.

5. Confirm Software Compatibility and Reporting Capabilities

An outsourced accounting provider should be able to work with your existing accounting systems or explain the benefits and costs of moving to another platform.

Common accounting platforms include QuickBooks Online, Xero, and other business accounting systems. The appropriate choice depends on your business requirements.

Ask potential providers:

  • Can you work within our existing accounting software?
  • Who owns the software subscription and financial data?
  • How are documents and receipts collected?
  • Can we access our books whenever needed?
  • What reports will we receive each month?
  • Can reports be customized for our management needs?
  • How are accounting errors or missing transactions identified?

A useful monthly reporting package generally includes a profit and loss statement, balance sheet, cash flow statement, and supporting reconciliation records where applicable.

Depending on your business, you may also need accounts receivable aging, accounts payable aging, budget comparisons, or department-level reporting.

Technology should make financial information easier to access and understand, not create another administrative burden.

6. Evaluate the Month-End Closing Process

Accurate bookkeeping is important, but businesses also need a reliable process for reviewing and finalizing their monthly accounts.

A structured month-end close helps identify missing transactions, unexplained differences, incorrect expense categories, and outstanding balances before financial reports are distributed.

Ask the provider to explain its closing process.

A typical process includes:

  1. Confirming that income and expenses have been recorded.
  2. Reconciling bank and credit card accounts.
  3. Reviewing outstanding invoices and customer balances.
  4. Recording relevant adjustments and accruals.
  5. Investigating unusual transactions.
  6. Reviewing the balance sheet and income statement.
  7. Obtaining appropriate internal review or approval.
  8. Delivering the finalized monthly reports.

Ask when the books will normally be closed after month-end and how delays will be communicated.

For example, a business might agree on a target of completing its monthly close within the first 10 business days, depending on transaction volume and the availability of required documents. The deadline should be realistic and agreed upon by both parties.

A dependable process is more valuable than an ambitious deadline that is regularly missed.

7. Establish Clear Communication and Accountability

Outsourcing accounting does not eliminate the need for communication. Your team still needs to provide documents, answer questions, approve transactions, and make business decisions.

Before choosing a provider, understand how communication will work.

Confirm the following:

  • Who will be your primary point of contact?
  • How quickly should you expect responses?
  • How will urgent accounting issues be handled?
  • Which documents must your team provide?
  • Who approves payments and unusual transactions?
  • How often will financial performance be reviewed?
  • What happens when the assigned accountant is unavailable?

A clear responsibility matrix can prevent tasks from being overlooked.

For example, the outsourced team might record vendor invoices and prepare a payment schedule, while your business retains final payment approval and control over bank transfers.

This separation helps maintain accountability and reduces the risk of unauthorized transactions.

8. Check Scalability and Flexibility

Your accounting requirements may change as your business grows.

A company that currently processes a few hundred transactions each month may eventually need multi-entity reporting, additional bank reconciliations, more detailed budgeting, or controller-level oversight.

Evaluate whether the provider can accommodate these changes.

Ask how fees and service levels change when transaction volumes increase, additional entities are added, or reporting requirements become more complex.

A scalable provider should explain how it manages increased workloads, assigns additional team members, and maintains review procedures.

You should also understand the process for reducing services if your requirements change.

The goal is to select a provider that can support your current needs without creating unnecessary costs or operational difficulties as your business evolves.

9. Review References, Agreements, and Exit Terms

Before making a final decision, verify the provider’s credibility and review the proposed contract carefully.

Where appropriate, ask for client references, examples of reporting packages, professional credentials, and documentation supporting relevant security claims.

The service agreement should clearly explain:

  • Services included in the engagement
  • Responsibilities of the provider and your business
  • Fees and billing terms
  • Expected reporting deadlines
  • Confidentiality and data protection obligations
  • Procedures for resolving errors
  • Contract renewal and termination terms
  • Data access and transfer arrangements when the engagement ends

Avoid relying solely on verbal promises made during a sales conversation.

Your business should be able to retrieve its accounting records and supporting documents if it changes providers. Confirm how the handover will work and whether any transition charges apply.

A clear exit plan reduces the risk of disruption if the relationship no longer meets your needs.

Outsourced Accounting vs. In-House Accounting

Both models can work well, depending on the size and complexity of a business.

Factor In-House Accounting Outsourced Accounting
Staffing Employees work directly for the business External professionals provide agreed services
Cost structure Salary, benefits, training, and software costs Contracted service fees and any additional charges
Oversight Direct day-to-day supervision Oversight through agreed processes and reporting
Expertise Depends on the employees hired May provide access to a broader team of specialists
Flexibility Additional capacity may require hiring Service scope may be adjusted by agreement
Communication Direct internal communication Requires clear communication procedures
Business knowledge Employees may develop detailed internal knowledge Provider needs documented processes and business context

Outsourcing is not automatically cheaper or better in every situation. A company with complex operations may benefit from an internal finance leader supported by an external accounting team.

The right model depends on your budget, transaction volume, reporting needs, and the level of financial oversight your business requires.

Common Mistakes to Avoid When Choosing an Accounting Provider

Businesses can encounter problems when they select a provider without defining expectations.

Avoid these common mistakes:

  • Choosing based only on the lowest price
  • Assuming all accounting services are included
  • Failing to check industry experience
  • Overlooking data security and access permissions
  • Accepting vague reporting deadlines
  • Not identifying who approves payments
  • Failing to review sample financial reports
  • Ignoring additional fees and onboarding costs
  • Giving the provider unrestricted access without considering appropriate controls
  • Signing an agreement without reviewing termination and data-transfer terms

Taking time to evaluate these areas can help your business establish a more dependable accounting relationship.

How Accountant Anywhere Can Support Your Accounting Needs

Managing bookkeeping, reconciliations, accounts payable, and financial reporting internally can become challenging as a business grows. An organized accounting process helps business owners maintain clearer records and make better-informed financial decisions.

Accountant Anywhere provides accounting-related support, including services for US-based property management businesses. Depending on your requirements, its team can help with tasks such as accounts payable processing, bank reconciliations, journal entries, and monthly financial reporting.

If your business operates in property management, explore Accountant Anywhere’s Property Management Accounting Services to learn more about the services available.

For other small businesses, confirm directly with the provider whether its current service scope matches your accounting requirements.

Frequently Asked Questions

1. What should a small business look for in an outsourced accounting provider?

Look for a provider with relevant experience, clearly defined services, appropriate data security, transparent pricing, reliable monthly reporting, and an agreed communication process. Check references and review the service agreement before making a decision.

2. Are outsourced accounting services suitable for small businesses in the USA?

Yes. Outsourcing can be useful for small businesses that need consistent bookkeeping and financial reporting but do not require every accounting task to be performed by a full-time internal team. Suitability depends on the company’s needs, budget, and complexity.

3. How much do outsourced accounting services cost?

Costs vary according to transaction volume, business complexity, service scope, reporting requirements, and the provider’s pricing model. Request itemized quotes from multiple providers and compare the included services rather than relying on the monthly fee alone.

4. Is outsourced accounting secure?

It can be, provided the business and provider use appropriate safeguards. Review access controls, multi-factor authentication, encryption, confidentiality agreements, backup procedures, and incident-response arrangements before sharing sensitive financial information.

5. Can an outsourced accounting provider handle taxes and payroll?

Some providers offer payroll-related accounting and tax services, while others focus primarily on bookkeeping and financial reporting. Confirm the exact scope and verify that any required tax or payroll work is handled by appropriately qualified professionals.

6. Will I still have access to my financial records?

Your agreement should specify that your business retains appropriate access to its financial records and supporting documents. Confirm software ownership, user permissions, data export options, and the process for transferring records if you change providers.

7. When should a business consider outsourcing accounting?

Consider outsourcing when bookkeeping falls behind, reconciliations are delayed, monthly reports arrive too late, internal staff lack the required expertise, or financial administration takes time away from core business activities.

Conclusion

Choosing an accounting provider is an important operational decision for any growing business. The right partner should offer services that match your requirements, protect financial information, provide reliable reporting, and communicate clearly about responsibilities and deadlines.

When comparing outsourced accounting services USA, evaluate the complete service package, accounting expertise, security practices, software compatibility, pricing, and contract terms. A structured evaluation helps you compare providers fairly and understand what your business will receive.

Start by identifying your current accounting challenges, documenting the tasks you want to outsource, and requesting written proposals from suitable providers. With clear expectations and appropriate controls, outsourced accounting can support more organized financial management as your business grows.

To learn more about Accountant Anywhere’s services, visit the official website or contact the team to discuss your requirements.

Rental Income vs Operating Expenses: A Property Manager’s Guide

Rental Income vs Operating Expenses: A Property Manager's Guide

Managing rental properties requires a clear understanding of how much money a property generates and how much it costs to operate. Although rental income shows the money coming into a property, operating expenses reveal how much is spent on maintaining the property, serving tenants, and managing daily operations.

For property managers, tracking rental property income and expenses is essential for understanding financial performance, preparing accurate reports, and making informed decisions. Without organized records, it can be difficult to determine whether a property is generating a healthy operating profit or experiencing rising costs.

In this guide, we explain the difference between rental income and operating expenses, explore common examples of each, and share practical ways to manage property finances more effectively.

What Is Rental Income?

Rental income is the money earned from leasing a residential or commercial property to tenants. It is generally the primary source of revenue for property owners, although additional income may come from other permitted property-related charges and services.

Common sources of rental income include:

  • Monthly rent payments from tenants
  • Parking fees, where applicable
  • Laundry or storage fees
  • Pet fees or other permitted charges
  • Income from additional services provided under the lease agreement
  • Late payment fees, where permitted by the lease and applicable law

Property managers should record each income transaction accurately and assign it to the correct property and accounting period. They should also distinguish between rent that has been collected and rent that is still outstanding.

For example, if a rental property generates $3,000 in monthly rent but a tenant pays only $2,500 by the end of the month, the accounting records should reflect the actual collection and any outstanding amount according to the accounting method being used.

Accurate income tracking helps property managers monitor rent collection, identify payment delays, and provide reliable financial reports to property owners.

What Are Operating Expenses?

Operating expenses are the recurring costs required to maintain a rental property and support its day-to-day operations. These expenses reduce the income available to cover other obligations and contribute to the property’s operating performance.

Typical operating expenses include:

1. Property Maintenance and Repairs

Property managers must regularly address repairs and maintenance to keep rental units safe, functional, and attractive to tenants.

Examples include plumbing repairs, electrical work, HVAC servicing, landscaping, pest control, and routine property inspections.

2. Property Management Fees

Property owners may pay management fees to a property management company for services such as tenant communication, rent collection, lease administration, and maintenance coordination.

These fees should be recorded consistently according to the management agreement and the property’s accounting procedures.

3. Utilities

Depending on the lease agreement, property owners may be responsible for electricity, water, gas, waste removal, or other utility expenses.

Property managers should verify which costs are the owner’s responsibility and which are paid directly by tenants.

4. Insurance

Property insurance may cover risks associated with buildings, liability, and other insured events. Premiums should be recorded in the appropriate expense category and monitored when policies renew.

5. Property Taxes

Property taxes are an important ownership cost in many rental property portfolios. Property managers should track payment deadlines and ensure that applicable tax obligations are reflected accurately in financial records.

6. Landscaping and Cleaning

Common-area cleaning, lawn care, snow removal, and other exterior maintenance services may be recurring expenses for residential communities and commercial properties.

7. Professional and Administrative Services

Property owners may also incur accounting fees, legal expenses, licensing costs, and other administrative charges related to property operations.

Not every cash outflow is an operating expense. Mortgage principal payments, capital improvements, security deposit movements, and certain other transactions may require different accounting treatment. Property managers should categorize these items correctly rather than treating every payment as an ordinary operating cost.

Rental Income vs Operating Expenses: Key Differences

Rental income and operating expenses represent two different sides of a property’s financial activity.

Factor Rental Income Operating Expenses
Meaning Money earned from renting the property Costs incurred to operate and maintain the property
Financial effect Increases revenue Reduces operating profit
Common examples Rent, permitted fees, parking income Repairs, management fees, utilities, insurance
Accounting purpose Measures income generated Measures the cost of operating the property
Reporting Recorded as income Recorded under appropriate expense categories
Management goal Improve collection and reduce vacancies Control costs without compromising property quality

Understanding this difference helps property managers prepare clearer financial statements and explain property performance to owners.

How to Calculate Rental Property Operating Profit

One of the simplest ways to evaluate a property’s operating performance is to subtract its operating expenses from its rental revenue.

Basic formula:

Net Operating Income (NOI) = Rental Income − Operating Expenses

Net operating income measures the income generated by a property after operating expenses but before certain financing and other non-operating items.

For example, consider a rental property with the following monthly figures:

Financial Item Monthly Amount
Rental income $4,000
Maintenance and repairs $300
Property management fees $400
Insurance $150
Utilities paid by the owner $200
Property taxes $350
Total operating expenses $1,400
Net operating income $2,600

In this example, the property generates $4,000 in rental income and incurs $1,400 in operating expenses, resulting in a monthly NOI of $2,600.

This calculation provides a useful snapshot of operating performance. However, it does not necessarily represent the owner’s final cash flow or taxable income. Mortgage payments, capital expenditures, income taxes, and other items may affect the final financial result.

Why Property Managers Should Track Income and Expenses Separately

Maintaining separate and accurate income and expense records provides several benefits.

1. Better Financial Visibility

When income and expenses are recorded separately, property managers can see how much a property earns and where the money is being spent.

This makes it easier to identify rising costs, investigate unexpected transactions, and understand changes in operating performance.

2. Improved Budgeting

Historical income and expense data helps property managers prepare more realistic budgets.

For example, if maintenance costs consistently increase during a particular season, managers can account for those costs when planning the next budget.

3. More Accurate Owner Reporting

Property owners need clear financial information to understand their investments. Organized records make it easier to prepare income statements, expense summaries, and other reports.

4. Faster Identification of Problems

A property may generate strong rental revenue while still experiencing declining profitability because of rising repair costs, higher insurance premiums, or increasing vacancies.

Reviewing income and expenses together helps property managers identify these issues earlier.

5. Better Property-Level Comparisons

For portfolios containing multiple rental properties, tracking each property’s financial activity separately allows managers to compare operating performance and identify properties that need additional attention.

Best Practices for Managing Rental Income and Operating Expenses

A consistent accounting process helps property managers maintain accurate financial records and make better decisions.

1. Maintain Separate Records for Each Property

Assign every transaction to the appropriate property. Avoid combining expenses from different properties in a way that makes individual performance difficult to measure.

Use property identification numbers, accounting categories, and consistent naming conventions to keep records organized.

2. Record Transactions Promptly

Record rent receipts, vendor invoices, maintenance costs, and other transactions regularly. Delayed data entry can lead to incomplete reports and make it harder to identify missing transactions.

3. Reconcile Bank Accounts Monthly

Compare accounting records with bank statements to confirm that deposits and payments have been recorded correctly. Investigate missing entries, unexpected charges, and discrepancies promptly.

4. Review Expenses Against the Budget

Compare actual operating costs with budgeted amounts each month. Investigate significant differences and determine whether they are caused by unexpected repairs, price increases, billing errors, or changes in property operations.

5. Monitor Outstanding Rent

Review unpaid rent and follow up according to the lease agreement and applicable procedures. Clear rent collection records help property managers understand outstanding balances and maintain more reliable financial reports.

6. Use Property Management Accounting Software

Accounting and property management systems can help centralize income records, vendor invoices, expense categories, and financial reporting.

Choose software that supports your portfolio’s size, reporting needs, and existing workflows. Automation can save time, but transactions should still be reviewed for accuracy.

7. Prepare Monthly Financial Reports

Monthly reports help property managers understand rental revenue, operating expenses, outstanding payments, and operating results.

Consistent reporting also makes it easier to compare performance across properties and reporting periods.

Common Mistakes to Avoid

Even experienced property managers can make errors when financial records are incomplete or processes are inconsistent.

Avoid these common mistakes:

  • Recording rent under the wrong property
  • Failing to follow up on unpaid rent
  • Mixing capital improvements with routine repairs
  • Recording the same expense more than once
  • Overlooking recurring vendor charges
  • Delaying bank reconciliation
  • Combining owner funds or tenant deposits with operating revenue
  • Failing to review expenses against the budget
  • Treating net operating income as the same as final cash flow

Correct expense classification is particularly important because different transactions may receive different accounting or tax treatment. Consult a qualified accounting professional when a transaction’s classification is unclear.

How Accountant Anywhere Can Help

Managing financial records across several rental properties can become time-consuming as transaction volumes increase. Property managers need organized bookkeeping processes, reliable expense tracking, accurate reconciliations, and consistent financial reports.

Accountant Anywhere offers property management accounting support that includes services such as accounts payable processing, bank reconciliations, journal entries, monthly financial statements, and budgeting support. These services can help property management businesses maintain organized records and improve visibility into property-level financial activity.

Learn more about Accountant Anywhere’s Property Management Accounting Services to explore the available support. The appropriate service scope will depend on your business’s needs and should be confirmed with the provider.

Frequently Asked Questions

1. What is the difference between rental income and operating expenses?

Rental income is the revenue earned from leasing a property, while operating expenses are the recurring costs associated with running and maintaining it. Comparing the two helps property managers evaluate operating performance.

2. What are common operating expenses for rental properties?

Common examples include maintenance and repairs, property management fees, insurance, property taxes, utilities paid by the owner, landscaping, and cleaning. The exact categories depend on the property and applicable accounting rules.

3. How do you calculate net operating income for a rental property?

Subtract operating expenses from the property’s operating revenue. The result is net operating income, which measures operating performance before certain financing and non-operating items.

4. Should property managers track income and expenses separately for each property?

Yes. Property-level tracking helps managers understand each property’s financial performance, prepare more accurate owner reports, compare operating costs, and identify unusual transactions.

5. How often should rental property income and expenses be reviewed?

Property managers should record transactions regularly, reconcile bank accounts on a consistent schedule, and review financial reports at least monthly in many routine operations. Larger or more complex portfolios may require more frequent monitoring.

6. Can accounting software help manage rental property finances?

Yes. Suitable software can organize transactions, track income and expenses, support bank reconciliation, and generate financial reports. Managers should choose tools that match their portfolio’s needs and review the resulting records for accuracy.

Conclusion

Understanding the difference between rental income and operating expenses is fundamental to effective property management. Accurate records help managers measure operating performance, monitor costs, improve budgeting, and provide property owners with clearer financial information.

By tracking rental property income and expenses consistently, reconciling accounts regularly, and reviewing monthly reports, property managers can identify financial issues earlier and make more informed decisions.

As a portfolio grows, standardized accounting processes and appropriate professional support can make financial management more efficient. Visit Accountant Anywhere or contact the team to discuss your property management accounting needs.

How to Manage Accounts Payable for Multiple Rental Properties

Manage Accounts Payable for Multiple Rental Properties

Managing multiple rental properties involves more than collecting rent and tracking income. Property managers must also handle vendor invoices, maintenance expenses, utility bills, contractor payments, insurance premiums, and other recurring costs. When these transactions come from different properties, keeping payments organized can become challenging.

A structured property management accounts payable process helps property managers pay vendors on time, control expenses, avoid duplicate payments, and maintain accurate financial records. With the right procedures and accounting systems, managing bills across multiple rental properties becomes more efficient and transparent.

What Is Accounts Payable in Property Management?

Accounts payable refers to the money a property management business owes to vendors, suppliers, contractors, and service providers for goods or services already received.

For rental properties, these obligations may include:

  • Plumbing, electrical, and HVAC repair invoices
  • Landscaping and cleaning service payments
  • Water, electricity, gas, and other utility bills
  • Property insurance premiums
  • Pest control and waste removal charges
  • Building maintenance and renovation expenses
  • Property management software subscriptions
  • Contractor and supplier invoices

When multiple rental properties are involved, each expense must be assigned to the correct property and recorded in the appropriate accounting category. Without a consistent process, property managers may struggle to identify which property incurred an expense, whether an invoice has been paid, or how much is owed to each vendor.

1. Organize Expenses by Property

The first step toward managing accounts payable effectively is to maintain separate financial records for each rental property.

Even when several properties belong to the same owner, their expenses should be tracked individually. For example, a plumbing repair at Property A should not accidentally be recorded as a maintenance expense for Property B.

Create a property-wise expense structure that includes:

  • Property name or identification number
  • Vendor or service provider
  • Invoice number and date
  • Expense category
  • Amount due
  • Payment due date
  • Payment status
  • Approval status

This structure makes it easier to review individual property expenses and prepare accurate financial reports. It also helps owners understand how much each property costs to maintain.

If you manage several rental units, using a property management accounting system can simplify expense allocation and reduce manual data entry.

2. Centralize Vendor Invoices

Receiving invoices through multiple email accounts, paper documents, messaging apps, and online portals can make payment management difficult. Important bills may be overlooked, while the same invoice could accidentally be entered more than once.

A centralized invoice management system helps prevent these problems.

Set up one designated process for receiving and recording vendor invoices. Every invoice should be stored digitally, labeled clearly, and entered into the accounting system as soon as it is received.

A useful invoice record should include the vendor’s name, invoice number, service description, property assignment, total amount, approval status, and payment deadline.

Digital invoice storage also makes it easier to retrieve supporting documents during financial reviews, owner reporting, or tax preparation.

3. Establish a Consistent Invoice Approval Process

Not every invoice should be paid immediately after it arrives. Property managers should first confirm that the service was authorized, completed, and billed correctly.

An effective approval process may include the following steps:

  1. Receive the invoice: Record the invoice in the accounts payable system.
  2. Verify the service: Confirm that the maintenance work or service was completed.
  3. Check the amount: Compare the invoice with the approved estimate, purchase order, or service agreement where applicable.
  4. Assign the property: Ensure the expense belongs to the correct rental property.
  5. Obtain approval: Request approval from the responsible property manager or owner when required.
  6. Schedule payment: Add the approved invoice to the payment calendar.

Clear approval rules reduce the risk of unauthorized expenses and help ensure that property funds are used appropriately.

For larger portfolios, you can also establish approval limits based on the invoice amount or type of work.

4. Track Payment Due Dates Carefully

Late payments can damage vendor relationships, interrupt essential services, and sometimes result in additional fees. When managing several properties, keeping track of every deadline manually can become unreliable.

A payment calendar provides a simple solution.

Record all upcoming payment deadlines and review them at least once a week. Categorize invoices according to their urgency, such as payments due within seven days, payments due later in the month, and overdue invoices requiring immediate attention.

Consider using automated reminders to notify the responsible team before a payment becomes overdue.

A well-maintained property management accounts payable workflow should also distinguish between invoices that have been received, approved, scheduled, paid, and reconciled. This makes the actual payment status clear to everyone involved.

5. Use Accounting Software to Improve Efficiency

Spreadsheets may work for a small number of rental units, but managing a growing portfolio often requires more structured tools.

Property management and accounting software can help centralize invoices, track payment obligations, assign expenses to individual properties, and generate financial reports.

When evaluating software, look for features such as:

  • Property-wise expense tracking
  • Vendor and invoice management
  • Payment reminders and approval workflows
  • Bank reconciliation capabilities
  • Recurring bill management
  • Digital document storage
  • Accounts payable reports
  • Integration with bookkeeping and accounting systems

Choose a solution that matches the size and complexity of your portfolio. Before adopting new software, review your current workflow and identify the tasks that consume the most time or create the most errors.

Automation can reduce repetitive administrative work, but invoices and payment records should still be reviewed for accuracy.

6. Prevent Duplicate Payments and Invoice Errors

Duplicate payments can occur when an invoice is submitted through multiple channels, recorded by different employees, or processed again because its payment status was not updated.

To reduce these risks, establish a few basic controls.

First, use invoice numbers to identify duplicate entries. If a vendor does not provide a unique invoice number, create a consistent reference based on the vendor, invoice date, and amount.

Second, update payment records immediately after a transaction is completed. Third, assign clear responsibility for invoice entry, approval, and payment wherever staffing allows.

Before paying an invoice, verify the vendor details, amount, property assignment, and previous payment history.

Regular reviews of outstanding invoices and vendor statements can also help identify discrepancies before they become larger accounting problems.

7. Reconcile Payments with Bank Statements

Recording a payment in accounting software does not automatically mean that the transaction has cleared the bank. Payments can be delayed, rejected, reversed, or recorded incorrectly.

Bank reconciliation helps confirm that the payments in your accounting records match the transactions shown on your bank statements.

During reconciliation, review outstanding payments, bank fees, duplicate transactions, missing entries, and any differences between recorded and actual balances.

For rental portfolios, property-level expense reports should also be checked against the supporting invoices and payment records.

Consistent reconciliation improves the reliability of financial information and helps property managers identify issues before preparing owner statements or monthly reports.

8. Monitor Vendor Costs and Recurring Expenses

Accounts payable records provide useful information about the operating costs of each rental property.

Review expenses regularly to identify increasing maintenance costs, unexpected invoices, repeated repairs, and opportunities to negotiate better vendor rates.

For example, if landscaping expenses rise significantly at one property, investigate whether the increase is related to additional services, seasonal requirements, or incorrect billing.

Recurring bills should also be reviewed periodically. Confirm that services are still required, contract rates remain accurate, and invoices match the agreed terms.

Comparing expenses across similar properties can help identify unusual costs. However, consider differences in property size, age, location, and maintenance needs before deciding that an expense is excessive.

9. Maintain Clear Records for Property Owners

Property owners need accurate information about the expenses associated with their investments. Organized accounts payable records make it easier to explain maintenance costs, vendor payments, and outstanding obligations.

Maintain supporting documentation for every significant transaction, including invoices, approvals, payment confirmations, and relevant service agreements.

Prepare regular reports showing expenses by property, vendor, and category. Include outstanding invoices and upcoming obligations where relevant.

Clear reporting helps owners understand where their money is being spent and supports more informed decisions about maintenance budgets and property investments.

For professional support with bookkeeping and financial reporting, explore Accountant Anywhere, which provides accounting-related services for businesses.

10. Review Accounts Payable Performance Every Month

A monthly review helps property managers identify issues and improve their payment processes.

Useful metrics include:

  • Total outstanding invoices
  • Number of overdue payments
  • Average time taken to process invoices
  • Duplicate or incorrect invoices identified
  • Total maintenance and operating expenses by property
  • Payments due during the next month
  • Differences identified during bank reconciliation

Reviewing these figures regularly can reveal bottlenecks in invoice approvals, recurring vendor issues, or properties with unusually high operating expenses.

Use the findings to improve approval procedures, update payment schedules, and strengthen financial controls.

Common Accounts Payable Mistakes to Avoid

Even an organized process can fail when basic accounting practices are overlooked. Avoid these common mistakes:

  • Recording expenses without assigning them to the correct property
  • Paying invoices before verifying the work
  • Missing payment deadlines
  • Entering the same invoice more than once
  • Failing to update payment statuses
  • Mixing personal and property-related expenses
  • Neglecting bank reconciliation
  • Keeping incomplete invoice documentation
  • Ignoring recurring increases in vendor costs

Addressing these issues early helps maintain accurate records and reduces unnecessary administrative work.

Frequently Asked Questions

1. What is the best way to manage accounts payable for multiple rental properties?

The best approach is to centralize invoices, maintain property-wise expense records, establish approval procedures, track payment deadlines, and reconcile payments regularly. Accounting software can make these tasks easier as the portfolio grows.

2. How often should rental property accounts payable be reviewed?

Upcoming payments should ideally be reviewed weekly, while a more detailed review of outstanding invoices, expenses, and reconciliations should take place monthly. High-volume portfolios may require more frequent monitoring.

3. How can property managers prevent duplicate vendor payments?

Use unique invoice references, maintain a centralized invoice register, verify payment status before processing bills, and reconcile vendor statements regularly. Clear responsibilities for invoice entry and payment approval also help reduce errors.

4. Why is property-wise expense tracking important?

Property-wise expense tracking helps owners understand the operating costs of each rental unit, supports accurate financial reporting, and makes it easier to identify unusual expenses or recurring maintenance issues.

5. When should a property manager outsource accounts payable?

Outsourcing may be worth considering when invoice volume increases, payment deadlines are frequently missed, bookkeeping errors become common, or internal staff cannot manage financial administration efficiently. The right choice depends on the portfolio’s size, complexity, and budget.

Conclusion

Managing vendor bills across multiple rental properties requires consistent processes, accurate records, and regular financial reviews. By organizing expenses by property, centralizing invoices, verifying approvals, tracking payment deadlines, and reconciling bank transactions, property managers can maintain better control over their financial obligations.

A reliable property management accounts payable process also improves vendor relationships, supports transparent owner reporting, and helps identify unnecessary operating costs. As a rental portfolio expands, standardized workflows and appropriate accounting technology can make financial management more accurate and efficient.

If your business needs support with bookkeeping and accounting processes, visit Accountant Anywhere or contact the team to explore suitable services.

Common Property Management Bookkeeping Mistakes and How to Avoid Them

Property management professionals reviewing rental income

Managing rental properties involves much more than collecting rent and coordinating maintenance. Property managers must also track rental income, record operating expenses, process vendor invoices, reconcile bank accounts, and prepare accurate financial reports for property owners. When these financial activities are not managed properly, small bookkeeping errors can develop into larger financial problems.

Accurate bookkeeping helps property management companies understand their financial position, maintain transparent records, and make informed business decisions. It also helps property owners understand how their investments are performing and how their money is being managed.

However, managing financial records across multiple properties can become complicated, particularly when businesses rely on spreadsheets, inconsistent procedures, or delayed transaction recording. Understanding common property management bookkeeping mistakes can help property managers improve their accounting processes and avoid unnecessary financial discrepancies.

In this guide, we explore the most common bookkeeping errors in property management, explain why they happen, and provide practical strategies to prevent them.

Why Accurate Bookkeeping Matters in Property Management

Property management bookkeeping involves recording and organizing the financial transactions associated with rental properties. These transactions may include rental payments, maintenance expenses, property management fees, insurance payments, utility bills, and vendor invoices.

Maintaining accurate records provides several important benefits.

Better financial visibility: Property managers can monitor rental income, expenses, outstanding balances, and available cash.

Improved owner communication: Organized financial statements help property owners understand property performance and financial activity.

Stronger expense control: Accurate records make it easier to identify unexpected costs and investigate unusual transactions.

Reliable financial reporting: Proper bookkeeping provides a stronger foundation for monthly statements, budgeting, tax preparation, and financial analysis.

Better decision-making: Property managers can use reliable financial information to evaluate rental performance, plan maintenance spending, and identify opportunities for improvement.

Without consistent bookkeeping procedures, property managers may struggle to understand where money is coming from, where it is going, and whether financial records accurately reflect actual transactions.

1. Mixing Financial Records From Different Properties

One of the most common bookkeeping problems occurs when transactions from multiple properties are recorded incorrectly or combined without proper identification.

Property management companies may oversee several rental units, residential buildings, or commercial properties. If income and expenses are not assigned to the correct property, financial reports can become inaccurate.

Why Does This Happen?

Common reasons include inconsistent transaction descriptions, incorrect account coding, manual data-entry errors, and inadequate bookkeeping systems.

For example, a property manager may accidentally record a maintenance invoice for Property A under Property B. Although the overall expense may be recorded, the individual property reports will be incorrect.

How to Avoid It

  • Maintain separate financial records for each property.
  • Use consistent property names and identification codes.
  • Assign every transaction to the appropriate property.
  • Review property-level income and expense reports monthly.
  • Use accounting software that supports property-level tracking.

Accurate property identification helps managers evaluate each property’s financial performance and provide reliable reports to owners.

2. Recording Rental Income Incorrectly

Rental income is one of the most important financial components of property management. Errors in recording rent payments can affect cash balances, tenant ledgers, and financial statements.

Problems may occur when payments are entered twice, received payments are not recorded, or rent is assigned to the wrong tenant or accounting period.

Example

Suppose a tenant pays $1,500 in monthly rent, but the payment is accidentally recorded twice. The accounting system may show more rental income than the property actually received.

Similarly, a payment received through an online portal may be missing from the accounting records if the transaction is not imported or reviewed correctly.

How to Avoid It

Property managers should establish a consistent rent-recording process.

  • Compare recorded payments with bank deposits and payment processor reports.
  • Match each payment to the correct tenant account.
  • Investigate duplicate transactions.
  • Review outstanding rent balances regularly.
  • Reconcile payment records with bank statements.

Automated payment records can reduce manual entry, but transactions should still be reviewed for accuracy.

3. Failing to Reconcile Bank Accounts Regularly

Bank reconciliation involves comparing accounting records with bank statements to identify differences and confirm that transactions have been recorded correctly.

When reconciliation is delayed, missing payments, duplicate entries, bank fees, and unexplained discrepancies may remain undetected.

Why Is Bank Reconciliation Important?

Consider a property management company that records a vendor payment of $800. If the payment is entered incorrectly as $80, the accounting balance will not match the bank statement.

A regular reconciliation helps identify the discrepancy so the accounting team can investigate and correct it.

How to Avoid It

  • Reconcile relevant bank accounts at least monthly.
  • Compare deposits and withdrawals with accounting entries.
  • Identify outstanding checks and deposits in transit.
  • Record applicable bank fees and interest.
  • Investigate unexplained differences before closing the books.

Property managers should also follow applicable requirements for trust accounts and tenant security deposit accounts.

Regular reconciliation improves the reliability of financial records and helps identify problems before they affect reporting.

4. Misclassifying Property Expenses

Property management businesses handle many different expenses, including repairs, utilities, insurance, cleaning, management fees, and capital improvements.

When expenses are assigned to incorrect categories, financial reports may not accurately represent the property’s operating performance.

For example, recording a significant capital improvement as an ordinary repair expense may distort operating expenses and affect how the property’s financial performance is evaluated.

The appropriate accounting treatment depends on the nature of the expenditure and the applicable accounting and tax rules.

How to Avoid It

Create a consistent chart of accounts that clearly identifies common property-related expenses.

Property managers should:

  • Establish clear expense categories.
  • Maintain documentation for invoices and payments.
  • Review unusual or high-value transactions.
  • Apply consistent classification procedures.
  • Consult a qualified accounting professional when treatment is uncertain.

Consistent expense classification makes budgeting, financial reporting, and year-over-year comparisons more useful.

5. Ignoring Accounts Payable and Vendor Invoices

Property managers regularly receive invoices from contractors, maintenance companies, cleaning services, utility providers, and other vendors.

If invoices are not recorded promptly, the business may overlook payment deadlines, incur late fees, or lose track of outstanding obligations.

Duplicate invoices can also lead to unnecessary payments.

How to Avoid It

Establish a structured invoice management process that includes:

  1. Recording each invoice when received.
  2. Verifying vendor details and invoice amounts.
  3. Assigning the expense to the correct property.
  4. Obtaining the required approval.
  5. Tracking payment deadlines.
  6. Confirming that payments are recorded correctly.

An accounts payable report can help property managers identify upcoming payments and overdue invoices.

Maintaining organized vendor records also makes it easier to investigate disputed charges and confirm that payments relate to legitimate services.

6. Overlooking Tenant Security Deposits

Security deposits require careful bookkeeping because refundable deposits generally represent amounts owed to tenants rather than rental income.

Recording a refundable deposit as ordinary rental income can distort financial statements and create problems when the deposit must be returned.

The handling of security deposits may also be subject to specific state or local requirements.

How to Avoid It

  • Record security deposits using the appropriate liability accounts.
  • Maintain detailed records for each tenant and property.
  • Reconcile deposit balances with relevant bank accounts.
  • Document authorized deductions and refunds.
  • Follow applicable legal requirements for holding and returning deposits.

Property managers should ensure that security deposit records remain separate from ordinary rental income and that any deductions are properly documented.

7. Delaying Bookkeeping Until the End of the Month

Postponing bookkeeping tasks can create unnecessary pressure and increase the likelihood of errors.

When transactions are entered weeks after they occur, invoices may be misplaced, payment details may be forgotten, and discrepancies can become more difficult to investigate.

Delayed bookkeeping also makes it harder for property managers to understand current financial performance.

How to Avoid It

Develop a recurring schedule for financial administration.

For example:

  • Record rental payments as they are received.
  • Enter vendor invoices promptly.
  • Categorize expenses throughout the month.
  • Review outstanding tenant balances regularly.
  • Reconcile bank accounts monthly.
  • Prepare and review financial reports after the accounting period closes.

Consistent transaction recording makes month-end reporting more efficient and reduces the need for extensive corrections.

8. Failing to Track Accounts Receivable

Accounts receivable represents amounts owed to the property management business. In rental property accounting, this may include unpaid rent, tenant charges, and other outstanding balances.

When overdue amounts are not monitored, property managers may overlook collection issues or fail to identify discrepancies in tenant accounts.

How to Avoid It

Use an accounts receivable aging report to organize outstanding balances according to how long they have remained unpaid.

Review the report regularly to identify:

  • Recently overdue payments.
  • Long-outstanding tenant balances.
  • Disputed charges.
  • Payments that have not been applied correctly.
  • Accounts requiring additional follow-up.

Before taking collection action, verify that each balance is accurate and that any recorded payments have been applied to the appropriate account.

Regular monitoring improves financial visibility and supports more consistent rent collection procedures.

9. Preparing Inaccurate Financial Reports for Property Owners

Property owners rely on financial reports to understand rental income, operating expenses, management fees, and available funds.

If reports contain missing transactions, incorrect expense classifications, or unexplained balances, owners may lose confidence in the management process.

Inaccurate reports can also make it difficult to compare property performance across different periods.

How to Avoid It

Before issuing owner statements, property managers should:

  • Verify rental income and recorded expenses.
  • Reconcile relevant bank accounts.
  • Review outstanding invoices and tenant balances.
  • Confirm that transactions belong to the correct property.
  • Investigate unusual changes in financial results.
  • Maintain supporting documentation.

Owner statements should follow a consistent format and clearly explain income, expenses, fees, reserves, and distributions as applicable.

Accurate and timely reporting helps property managers maintain transparent relationships with property owners.

10. Relying Entirely on Spreadsheets or Manual Processes

Spreadsheets can be useful for basic tracking, but they may become difficult to manage as a property portfolio grows.

Manual systems can increase the risk of duplicate entries, formula errors, missing transactions, inconsistent records, and unauthorized changes.

These problems become more significant when several employees handle financial information across multiple properties.

How to Avoid It

Consider using property management accounting software that supports:

  • Property-level income and expense tracking.
  • Rent collection and payment records.
  • Bank reconciliation.
  • Vendor invoice management.
  • Accounts receivable and payable reporting.
  • Financial statements and owner reports.
  • Appropriate user permissions and audit trails.

Software should match the size and complexity of the business. Even with automation, property managers must maintain proper procedures, review reports, and verify financial information.

Best Practices to Improve Property Management Bookkeeping

Preventing bookkeeping errors requires more than correcting individual transactions. Property managers should establish consistent procedures that support accuracy throughout the accounting process.

Maintain Standard Operating Procedures

Document how transactions should be recorded, categorized, reviewed, and approved. Consistent procedures help reduce errors when responsibilities are shared across a team.

Schedule Regular Financial Reviews

Review income, expenses, outstanding balances, and cash flow at defined intervals. Monthly reviews help identify unusual activity before it becomes a larger problem.

Keep Supporting Documents Organized

Store invoices, receipts, bank statements, lease records, and payment confirmations in an organized system. Supporting documents make it easier to verify transactions and resolve discrepancies.

Separate Duties Where Practical

Where staffing allows, separate transaction entry, approval, payment authorization, and reconciliation responsibilities. This helps strengthen internal controls and reduce the risk of errors or unauthorized transactions.

Seek Professional Accounting Support

As property portfolios grow, managing bookkeeping internally can become increasingly time-consuming. Professional accounting support can help businesses maintain organized records, reconcile accounts, and prepare financial reports.

By following these practices, property managers can reduce recurring errors and establish a more reliable accounting process.

How Professional Property Management Accounting Services Can Help

Managing the finances of multiple properties requires consistent transaction recording, careful reconciliation, accurate expense classification, and timely financial reporting.

For property management companies experiencing increasing workloads, professional accounting support can help organize recurring tasks and improve the consistency of financial records.

Accountant Anywhere provides property management accounting support for businesses that need assistance with bookkeeping and related financial processes.

Explore our Property Management Accounting Services to learn more about the available services and how professional accounting support may fit your business requirements.

The right accounting workflow can help property managers spend less time correcting errors and more time focusing on tenants, property owners, and daily operations.

Frequently Asked Questions

1. What are the most common property management bookkeeping mistakes?

Common mistakes include mixing financial records between properties, recording rental income incorrectly, failing to reconcile bank accounts, misclassifying expenses, overlooking security deposits, and delaying financial reporting.

2. How often should property management accounts be reconciled?

Monthly reconciliation is a common practice. Businesses with higher transaction volumes or specific contractual and regulatory requirements may need more frequent reviews.

3. Why is it important to separate financial records for each property?

Separate property-level records help managers track income and expenses accurately, evaluate individual property performance, and prepare reliable owner statements.

4. How can accounting software reduce bookkeeping errors?

Accounting software can help organize transactions, automate certain recurring tasks, generate financial reports, and maintain transaction histories. However, accurate results still depend on proper configuration, correct data entry, and regular review.

5. Should property management companies outsource bookkeeping?

Outsourcing may be useful for businesses that need additional accounting capacity or support with recurring tasks. Before choosing a provider, evaluate its property accounting experience, service scope, data security, reporting procedures, and quality controls.

6. How can property managers improve financial reporting accuracy?

Property managers can improve accuracy by recording transactions promptly, reconciling bank accounts, maintaining supporting documents, reviewing expense classifications, and verifying financial statements before distributing them to owners.

Conclusion

Accurate bookkeeping is essential for managing rental properties effectively. From recording rental income and classifying expenses to reconciling bank accounts and preparing owner statements, every financial task contributes to the reliability of a property’s accounting records.

Understanding property management bookkeeping mistakes helps property managers identify weaknesses in their existing processes and take practical steps to prevent recurring problems.

By maintaining property-level records, using appropriate accounting software, reviewing transactions regularly, and establishing consistent financial procedures, businesses can improve reporting accuracy and strengthen financial control.

For property managers handling growing portfolios, professional accounting support may also help reduce administrative pressure and maintain organized financial records.

Ultimately, preventing property management bookkeeping mistakes is about building reliable systems that support accurate reporting, transparent owner communication, and better long-term property management.

Explore Property Management Accounting Services

Looking to improve your property bookkeeping and financial reporting processes? Visit Accountant Anywhere to explore accounting services for businesses.

Need professional accounting support? Contact Accountant Anywhere to discuss your bookkeeping requirements and explore suitable solutions for your property management business.

When Should a Growing Business Hire a Fractional CFO?

fractional CFO services for small business

Growing a business requires more than increasing sales and acquiring new customers. As a company expands, financial decisions become more complex. Business owners must manage cash flow, control operating expenses, plan budgets, monitor profitability, and make informed decisions about future investments. Without a clear financial strategy, even a profitable business can experience financial difficulties.

Many small and medium-sized businesses reach a stage where basic bookkeeping and traditional accounting services are no longer enough to support their growth. They need financial insights, forecasting, and strategic guidance but may not have the budget or workload to justify hiring a full-time Chief Financial Officer (CFO).

This is where a fractional CFO can make a difference. A fractional CFO provides financial leadership on a part-time, contract, or flexible basis, helping businesses make informed decisions without the expense of maintaining a full-time executive.

For companies seeking fractional CFO services for small business, this approach can provide access to strategic financial expertise while allowing owners to focus on operations, customers, and long-term growth.

In this guide, we explain what a fractional CFO does, the signs that your business may need one, the benefits of hiring one, and how to determine the right time to bring financial leadership into your organization.

What Is a Fractional CFO?

A fractional CFO is an experienced financial professional who works with a business on a part-time or contract basis. Instead of being employed full-time, the CFO provides financial leadership according to the company’s requirements.

Their responsibilities extend beyond recording transactions and preparing financial statements. They help business owners understand financial performance, evaluate risks, develop budgets, forecast cash flow, and create strategies for sustainable growth.

Depending on the agreement, a fractional CFO may assist with:

  • Financial planning and forecasting
  • Cash flow management
  • Budget preparation and monitoring
  • Profitability analysis
  • Financial performance reporting
  • Business expansion planning
  • Cost optimization
  • Fundraising and financing preparation
  • Financial risk management
  • Strategic decision-making

A bookkeeper typically records financial transactions, while an accountant helps prepare and analyze financial records. A CFO uses financial information to guide business strategy and future planning.

For growing companies, this additional perspective can help connect everyday financial activities with broader business objectives.

7 Signs Your Growing Business Needs a Fractional CFO

Not every business needs a CFO immediately. However, certain challenges indicate that additional financial leadership may be valuable.

1. Your Cash Flow Has Become Difficult to Manage

Cash flow is one of the most important factors affecting business stability.

Even when sales are increasing, a company may experience cash shortages because customers pay late, operating expenses rise, or inventory and staffing require significant upfront investment.

A fractional CFO can analyze cash inflows and outflows, develop cash flow forecasts, and identify potential funding gaps before they become urgent problems.

For example, a business may receive large customer orders but need to pay suppliers several weeks before collecting customer payments. A cash flow forecast can help the owner prepare for this timing difference.

If your business frequently struggles to determine how much cash will be available in the coming months, it may be time to consider professional financial leadership.

2. Your Business Is Growing but Profitability Is Unclear

Revenue growth does not always translate into higher profits.

A company may increase sales while experiencing rising payroll costs, marketing expenses, supplier charges, or other operating costs. Without detailed financial analysis, it can be difficult to identify which products, services, or customer segments generate the strongest margins.

A fractional CFO can review financial performance, analyze expenses, and help identify opportunities to improve profitability.

They may also develop key performance indicators (KPIs) that allow management to track profit margins, operating costs, customer acquisition expenses, and other important measures.

This information helps business owners make decisions based on actual financial performance rather than revenue figures alone.

3. You Are Planning to Expand Your Business

Expansion can create new opportunities, but it also introduces financial risks.

Opening another location, hiring additional employees, entering a new market, or launching a new product may require significant investment.

Before committing resources, business owners need to understand the expected costs, potential returns, funding requirements, and possible risks.

A fractional CFO can prepare financial projections, evaluate different growth scenarios, and estimate how expansion may affect cash flow and profitability.

This allows business owners to compare opportunities and establish realistic financial targets before making major commitments.

4. Financial Decisions Are Taking Too Much of Your Time

Many small-business owners manage financial decisions alongside sales, customer service, operations, hiring, and marketing.

As the company grows, reviewing reports, preparing budgets, monitoring expenses, and evaluating investments can become increasingly time-consuming.

A fractional CFO can help organize financial information and provide structured recommendations, allowing business owners to focus more effectively on their primary responsibilities.

The objective is not to remove the owner from financial decision-making. Instead, it is to provide the analysis and guidance needed to make decisions with greater confidence.

5. You Need Better Budgeting and Financial Forecasting

Historical financial statements show what has already happened, but growing businesses also need to understand what may happen next.

Without reliable forecasts, companies may struggle to estimate future expenses, plan hiring, manage seasonal demand, or determine when additional funding will be required.

A fractional CFO can help create budgets, prepare rolling forecasts, compare actual results against expectations, and update financial plans when business conditions change.

For example, if sales are expected to increase significantly over the next six months, financial forecasting can help estimate the additional staffing, inventory, technology, and working capital required to support that growth.

6. You Are Preparing for Funding or Investment

Businesses seeking loans, investors, or other financing often need organized financial information and a clear explanation of their growth strategy.

Potential lenders and investors may want to review financial statements, cash flow projections, profitability trends, business risks, and future funding requirements.

A fractional CFO can help prepare financial models, evaluate financing options, organize supporting documentation, and explain the company’s financial position.

Although a CFO cannot guarantee funding approval, professional financial preparation can help a business present its financial information more clearly.

7. Your Existing Accounting Support Is No Longer Enough

Bookkeeping and accounting services are essential for maintaining accurate records and meeting financial reporting requirements.

However, as a company becomes more complex, it may also need strategic guidance on pricing, profitability, budgeting, financing, and long-term planning.

If your current accounting process tells you what happened financially but does not provide enough insight into what to do next, additional financial leadership may be beneficial.

Fractional CFO services for small business can bridge this gap by combining financial analysis with forward-looking planning and strategic recommendations.

What Does a Fractional CFO Actually Do?

A fractional CFO’s responsibilities depend on the company’s size, industry, financial position, and goals. Their work generally focuses on improving financial visibility and supporting better business decisions.

Financial Planning and Forecasting

The CFO develops financial projections based on expected revenue, operating expenses, cash flow, and planned investments.

These forecasts help management prepare for upcoming financial requirements and evaluate different business scenarios.

Cash Flow Optimization

A fractional CFO examines payment cycles, receivables, supplier terms, and recurring expenses to identify opportunities to improve cash flow.

They may recommend changes to payment schedules, collection processes, or working capital management.

Budget Development

The CFO works with management to establish financial targets and allocate resources effectively.

Regular budget reviews help identify unexpected expenses and determine whether the business needs to adjust its spending plans.

Financial Performance Analysis

A fractional CFO reviews financial statements and KPIs to understand the company’s performance.

This may include analyzing profit margins, operating expenses, revenue trends, and department-level performance.

Strategic Business Advice

Financial information can help management evaluate pricing changes, expansion opportunities, hiring plans, and investments.

A fractional CFO provides financial analysis to support these decisions while helping the business understand the potential risks and rewards.

Fractional CFO vs. Full-Time CFO: Which Is Better?

The right choice depends on your company’s financial complexity, budget, and need for executive support.

A full-time CFO works within the organization and provides ongoing financial leadership as part of the internal management team. This arrangement may suit larger companies with complex operations, extensive financing requirements, or substantial daily financial management needs.

A fractional CFO provides similar types of strategic financial support on a more flexible basis. The engagement may involve a set number of hours, specific projects, or recurring advisory sessions.

For a growing business that needs forecasting, cash flow planning, and profitability analysis but does not require a full-time executive, a fractional arrangement may be more practical.

However, businesses should compare the actual scope of work, availability, experience, and total cost rather than assuming that every fractional engagement is automatically less expensive.

How Much Does a Fractional CFO Cost?

The cost of a fractional CFO depends on several factors, including the professional’s experience, the complexity of the business, the number of hours required, and the scope of services.

Some arrangements use a monthly retainer, while others charge hourly rates or project-based fees.

A business requiring occasional financial reviews may need a different level of support from a company preparing for a major acquisition or fundraising process.

Before selecting a service, consider:

  • The number of hours or meetings included
  • The financial reports and forecasts to be prepared
  • The level of strategic involvement required
  • Whether implementation support is included
  • The frequency of performance reviews
  • Any additional project fees

The goal should be to find a service arrangement that addresses your financial challenges and delivers value relative to its cost.

How to Choose the Right Fractional CFO for Your Business

Choosing the right professional is important because financial recommendations can influence major business decisions.

Consider the following factors before making a decision.

Relevant experience: Look for experience with businesses of a similar size, industry, or growth stage.

Financial expertise: Evaluate the professional’s knowledge of budgeting, cash flow management, forecasting, profitability analysis, and financial planning.

Communication: Choose someone who can explain financial information clearly and translate complex data into practical recommendations.

Technology and reporting: Confirm compatibility with your accounting systems and reporting processes.

Service scope: Establish the responsibilities, expected deliverables, meeting schedule, and level of ongoing involvement.

Business alignment: Make sure the professional understands your company’s goals, financial challenges, and long-term plans.

Measurable objectives: Define what success should look like, such as improved forecasting accuracy, clearer reporting, stronger cash flow visibility, or better cost control.

A well-defined engagement helps both parties understand their responsibilities and measure progress over time.

Frequently Asked Questions

1. When should a small business hire a fractional CFO?

A small business should consider hiring a fractional CFO when financial decisions become more complex, cash flow is difficult to predict, profitability is unclear, or the company needs strategic financial guidance but does not require a full-time CFO.

2. Are fractional CFO services suitable for startups?

Yes. Startups may benefit from financial forecasting, budgeting, cash flow planning, and funding preparation. The appropriate level of support depends on the startup’s financial complexity, available budget, and growth plans.

3. What is the difference between a fractional CFO and an accountant?

An accountant generally focuses on financial records, reporting, compliance, and related accounting responsibilities. A fractional CFO focuses more on financial strategy, forecasting, profitability, cash flow planning, and business decision support. The responsibilities can overlap depending on the engagement.

4. Can a fractional CFO help improve profitability?

A fractional CFO can analyze margins, operating expenses, pricing, and financial performance to identify potential improvements. Actual results depend on the business’s circumstances and the implementation of recommended changes.

5. How often does a fractional CFO work with a business?

The frequency varies according to the agreement. Some businesses require regular monthly reviews, while others need more frequent involvement during expansion, fundraising, or significant financial changes.

6. Is hiring a fractional CFO better than hiring a full-time CFO?

A fractional arrangement may suit businesses that need strategic financial guidance without requiring a full-time executive. Larger or more complex organizations may benefit from a dedicated internal CFO. The right choice depends on workload, budget, and business requirements.

Conclusion

Hiring a fractional CFO can be an important step for a growing business that needs stronger financial planning and strategic guidance.

When cash flow becomes difficult to manage, profitability is unclear, expansion requires careful planning, or financial decisions consume too much management time, a fractional CFO can help bring structure and clarity to the process.

Rather than relying only on historical financial statements, businesses can use forecasting, budgeting, performance analysis, and financial planning to prepare for future challenges and opportunities.

The key is to identify your company’s financial needs, establish clear objectives, and choose a professional whose experience matches your business goals.

For growing companies that need experienced financial guidance without immediately hiring a full-time executive, fractional CFO services for small business can provide a flexible approach to improving financial visibility and supporting sustainable growth.

Explore Accounting and Financial Support

Looking for professional accounting support to help your business maintain accurate financial records and improve financial visibility? Visit Accountant Anywhere to explore its accounting services.

You can also learn more about its Property Management Accounting Services to understand how professional accounting support can help businesses manage financial records, reporting, and bookkeeping requirements.

Ready to discuss your business needs? Contact Accountant Anywhere to discuss your accounting requirements and explore suitable support options.

Real Estate Accounting Reports Every Property Manager Should Track

eal Estate Accounting Reports Every Property Manager

Managing real estate properties requires more than collecting rent and coordinating maintenance. Property managers must also monitor rental income, control operating expenses, manage vendor payments, track outstanding balances, and prepare accurate financial statements. Without organized financial reporting, it becomes difficult to understand whether a property is performing well or requires operational improvements.

Accounting reports help property managers understand where money comes from, how it is spent, and how much cash remains available. They also provide property owners with a clearer picture of their investments and support better financial decision-making.

For businesses managing multiple residential, commercial, or multifamily properties, property management financial reports are essential for monitoring performance, identifying financial discrepancies, and maintaining transparent records.

In this guide, we explore the most important real estate accounting reports every property manager should track, explain what each report reveals, and share practical tips for improving financial reporting.

Why Are Accounting Reports Important for Property Managers?

Accounting reports transform financial transactions into useful information. Instead of reviewing individual receipts, invoices, and bank transactions, property managers can use structured reports to evaluate the financial position of each property.

Here are some key benefits of maintaining accurate accounting reports.

1. Better Financial Visibility

Financial reports help property managers understand rental income, operating expenses, outstanding payments, and available cash. This information makes it easier to identify potential problems before they affect day-to-day operations.

2. Improved Expense Management

Regular reporting helps managers identify properties with unusually high maintenance costs, increasing utility expenses, or other unexpected charges. Investigating these changes can reveal opportunities to control spending.

3. Transparent Owner Communication

Property owners want to understand how their investments are performing. Clear financial statements help explain income, expenses, outstanding obligations, and distributions without requiring owners to examine every transaction individually.

4. More Informed Business Decisions

Financial reports support decisions about rental pricing, maintenance budgets, property improvements, and future investments. Accurate data allows property managers to evaluate options using actual financial performance rather than assumptions.

1. Profit and Loss Statement

A profit and loss statement, also known as an income statement, summarizes a property’s income and expenses over a specific period.

It helps property managers determine whether rental operations generated a profit or a loss during the reporting period.

What Does It Include?

A typical property-level profit and loss statement includes:

  • Rental income
  • Late fees and other applicable income
  • Maintenance and repair expenses
  • Property management fees
  • Insurance expenses
  • Utilities and cleaning costs
  • Property taxes
  • Other operating expenses
  • Net operating income or net profit, depending on the report’s format

Why Should You Track It?

Reviewing this report monthly helps property managers identify changes in operating costs and rental income.

For example, if rental income remains stable but maintenance expenses increase significantly, the manager can investigate whether the change results from recurring repairs, an unexpected issue, or incorrect expense coding.

It is important to understand the report’s format. Net operating income generally excludes certain items, such as debt service and income taxes, while net profit may include additional income and expenses.

2. Cash Flow Statement

A cash flow statement tracks money entering and leaving a business during a particular period. It helps property managers understand whether sufficient cash is available to meet upcoming financial obligations.

A property can appear profitable on an income statement while experiencing cash shortages because of unpaid rent, debt payments, capital improvements, or the timing of vendor payments.

What Should You Monitor?

Important cash flow items include:

  • Rental payments received
  • Payments made to vendors
  • Operating expenses paid
  • Mortgage or loan payments
  • Capital improvement spending
  • Owner distributions
  • Transfers between relevant accounts

How Does It Help?

Suppose a property generates consistent rental income but requires a major roof repair. The expense may create a temporary cash shortage even if the property remains profitable over the longer term.

A cash flow report helps managers understand the timing of receipts and payments, plan upcoming expenses, and determine whether additional funds may be required.

Property managers should also distinguish between operating cash and funds held for specific purposes, such as tenant security deposits or required reserves.

3. Rent Roll Report

A rent roll provides a property-level summary of tenants, rental units, lease information, and rental amounts.

It is particularly useful for residential and multifamily property managers who need to monitor occupancy, rental income, and tenant balances.

What Does a Rent Roll Show?

Depending on the system, a rent roll may include:

  • Unit numbers and tenant names
  • Lease start and end dates
  • Contracted rental amounts
  • Occupancy status
  • Vacant units
  • Outstanding tenant balances
  • Lease expiration information
  • Other relevant rental details

Why Is It Important?

The rent roll helps property managers compare expected rental income with actual collection results.

For example, if a building contains 20 rental units but three are vacant, the manager can investigate how those vacancies affect potential income.

The report can also help identify leases approaching expiration, unpaid rent, and inconsistencies between lease records and accounting data.

However, a rent roll does not always show the full financial picture. Managers should compare it with collection reports and accounting records to understand actual cash received.

4. Balance Sheet

A balance sheet shows a property’s or business’s financial position at a specific point in time. It summarizes assets, liabilities, and equity.

Unlike a profit and loss statement, which covers a period, a balance sheet represents a financial snapshot as of a particular date.

What Does It Include?

Common balance sheet items include:

  • Cash and bank balances
  • Accounts receivable
  • Other recorded assets
  • Accounts payable
  • Loans and mortgage liabilities
  • Tenant security deposit liabilities
  • Other outstanding obligations
  • Owner’s equity or other applicable equity balances

Why Should Property Managers Review It?

The balance sheet helps managers identify outstanding liabilities, monitor receivables, and verify that recorded balances are supported by appropriate documentation.

For example, if a business has a significant accounts payable balance, the manager can investigate upcoming obligations and determine whether sufficient funds are available to meet them.

Security deposits also require careful attention. Refundable tenant deposits generally represent liabilities rather than rental income, and their accounting treatment should follow applicable requirements.

5. Accounts Receivable Aging Report

An accounts receivable aging report shows unpaid amounts and how long they have remained outstanding.

In property management, this report commonly helps track overdue rent, tenant charges, and other amounts owed to the business.

Common Aging Categories

An aging report may organize balances into categories such as:

  • Current
  • 1–30 days overdue
  • 31–60 days overdue
  • 61–90 days overdue
  • More than 90 days overdue

The exact categories may vary depending on the accounting system.

How Does It Help?

The report helps property managers identify overdue balances and prioritize follow-up activities.

For example, a tenant with an unpaid balance that has remained outstanding for 60 days may require additional attention compared with a tenant whose payment is only a few days late.

Managers should investigate disputed charges, unapplied payments, and accounting errors before treating every outstanding balance as a collection problem.

Regular review can improve collection visibility and help reduce the risk of uncollectible amounts.

6. Accounts Payable Report

An accounts payable report summarizes amounts owed to vendors, contractors, service providers, and other suppliers.

Property managers regularly receive invoices for repairs, landscaping, cleaning, utilities, insurance, and other property-related services.

What Should You Review?

A useful accounts payable report may show:

  • Vendor names
  • Invoice numbers
  • Invoice dates
  • Outstanding amounts
  • Payment due dates
  • Overdue invoices
  • Property or expense classifications
  • Payment status

Why Is It Important?

Reviewing accounts payable helps property managers plan payments, avoid unnecessary late fees, and maintain good relationships with vendors.

It also helps identify duplicate invoices, incorrectly assigned expenses, and invoices that require additional approval.

Managers should establish clear procedures for invoice verification and payment authorization. Accounting reports should support these controls rather than replace them.

7. Budget vs. Actual Report

A budget vs. actual report compares planned income and expenses with the amounts recorded during a specific period.

This report helps property managers understand whether a property is performing according to its financial plan.

What Does It Show?

A typical report compares:

  • Budgeted rental income with actual income
  • Planned maintenance costs with actual expenses
  • Expected utility costs with recorded charges
  • Budgeted management expenses with actual costs
  • Forecast spending with current financial results

It may also show the amount and percentage of variance.

How Can It Improve Property Performance?

Suppose a property has a monthly maintenance budget of $3,000 but records $4,500 in actual maintenance expenses.

The report highlights a $1,500 unfavorable variance. The property manager can investigate whether the increase resulted from emergency repairs, recurring maintenance problems, or expenses that were not included in the original budget.

Not every unfavorable variance indicates poor management. Unexpected repairs may be necessary, while some favorable variances may simply reflect delayed spending.

The goal is to understand the reason for each significant difference and determine whether the budget or operating plan needs adjustment.

8. Bank Reconciliation Report

A bank reconciliation report helps confirm that accounting records agree with bank activity after accounting for valid timing differences and other reconciling items.

Regular reconciliation is essential because even small transaction errors can affect financial reporting when they remain unresolved.

What Should Be Checked?

Property managers and accounting teams should review:

  • Recorded deposits
  • Cleared payments
  • Outstanding checks
  • Deposits in transit
  • Bank fees and interest
  • Duplicate transactions
  • Missing entries
  • Unexplained differences

Why Does It Matter?

For example, an accounting system may show a payment that has not yet cleared the bank. This may represent a normal timing difference.

However, if the difference cannot be explained by outstanding transactions or other valid items, the accounting team should investigate it before finalizing the reconciliation.

Bank reconciliations should also be completed for relevant property and trust accounts according to applicable requirements.

9. Owner Statement

An owner statement summarizes the financial activity associated with a property over a particular period. It helps owners understand rental income, expenses, fees, and distributions.

The statement’s exact format depends on the management agreement and the reporting system.

What Is Typically Included?

An owner statement may contain:

  • Opening balance
  • Rental income received
  • Other property income
  • Operating expenses
  • Management fees
  • Reserve contributions or withdrawals
  • Owner distributions
  • Closing balance

Why Is It Important?

Property owners need accurate information to evaluate their investments and understand how their funds are being used.

Before distributing an owner statement, property managers should verify the supporting transactions, confirm that expenses are assigned to the correct property, and ensure that distributions reflect available funds and applicable obligations.

Clear owner statements can improve communication and reduce questions about unexplained deductions or balances.

10. Occupancy and Property Performance Report

Financial reporting becomes more useful when it is combined with operational information.

An occupancy and property performance report helps managers understand how vacancies, rental rates, and operating costs affect the financial performance of a property.

Key Metrics to Track

Depending on the property type, managers may monitor:

  • Occupancy rate
  • Vacancy rate
  • Average rental income per occupied unit
  • Rental income lost through vacancies
  • Operating expenses per unit
  • Net operating income
  • Lease renewal activity

For example, a property with increasing vacancy rates may experience lower rental income even when operating expenses remain stable.

By reviewing occupancy alongside financial reports, property managers can identify whether performance issues relate to rental pricing, tenant turnover, maintenance delays, or other operational factors.

Different property types require different performance measures, so managers should choose metrics that reflect their portfolio and business objectives.

Best Practices for Managing Property Accounting Reports

Maintaining accurate reports requires consistent accounting procedures and regular financial reviews.

Review Reports Monthly

Monthly reviews help identify discrepancies, overdue balances, unexpected expenses, and cash flow concerns before they become more difficult to resolve.

Maintain Separate Records for Each Property

Use consistent property identifiers and accounting categories to prevent transactions from being assigned to the wrong property.

Reconcile Bank Accounts Regularly

Compare bank statements with accounting records and document unresolved differences.

Use Appropriate Accounting Software

Property management and accounting platforms can simplify transaction tracking, financial reporting, and recurring reconciliations. Businesses should choose systems that support their portfolio and reporting requirements.

Document Significant Variances

Investigate unusual changes in income, expenses, occupancy, and cash balances. Record the reason for significant differences and any action taken.

Protect Financial Information

Limit system access according to job responsibilities and use appropriate safeguards when storing or sharing financial documents.

Following these practices makes property management financial reports more reliable and helps property managers use accounting information effectively.

How Professional Accounting Support Can Help

Preparing accurate reports requires organized bookkeeping, timely transaction recording, regular reconciliations, and consistent review procedures.

As property portfolios grow, these responsibilities can place additional pressure on internal teams. Professional property accounting support may help businesses manage recurring tasks such as accounts payable processing, bank reconciliations, journal entries, monthly financial statements, and annual budgeting.

Accountant Anywhere provides outsourced accounting support for property management companies handling residential, commercial, and other property types.

Learn more about its Property Management Accounting Services to explore the available support for your accounting operations.

The right accounting process can help property managers spend less time resolving financial discrepancies and more time improving property operations.

Frequently Asked Questions

1. What financial reports should property managers review monthly?

Property managers commonly review profit and loss statements, cash flow reports, rent rolls, balance sheets, accounts receivable aging reports, accounts payable reports, bank reconciliations, and owner statements. Budget comparisons and occupancy reports can provide additional insight.

2. Why are property management financial reports important?

These reports help property managers monitor income and expenses, identify overdue balances, evaluate property performance, maintain accurate financial records, and provide transparent information to property owners.

3. What is the difference between a profit and loss statement and a cash flow statement?

A profit and loss statement summarizes income and expenses over a period, while a cash flow statement tracks cash entering and leaving the business. The two reports provide different but complementary financial information.

4. How often should property accounts be reconciled?

Monthly reconciliation is a common practice. Businesses with high transaction volumes or specific contractual or regulatory requirements may need more frequent reviews.

5. Can accounting software generate property management reports automatically?

Many property management platforms can generate reports using recorded financial and operational data. However, report accuracy depends on correct transaction entry, account setup, configuration, and appropriate review.

6. Should property managers outsource financial reporting?

Outsourcing may help businesses that need additional accounting capacity or want support with recurring financial tasks. Before selecting a provider, evaluate its property accounting experience, service scope, reporting procedures, security practices, and quality controls.

Conclusion

Accurate accounting reports help property managers understand financial performance, maintain control over expenses, monitor cash flow, and provide clear information to property owners.

From profit and loss statements and cash flow reports to rent rolls, bank reconciliations, and owner statements, each report serves a specific purpose. Reviewing them together provides a more complete picture of a property’s financial and operational condition.

By establishing consistent reporting schedules, maintaining organized records, and investigating discrepancies promptly, property management businesses can make better-informed decisions and improve financial accountability.

Ultimately, property management financial reports are not simply documents prepared for recordkeeping. They are practical tools that help property managers identify risks, evaluate opportunities, and support the long-term performance of their real estate portfolios.

Explore Property Management Accounting Services

Looking to improve your property accounting and financial reporting processes? Visit Accountant Anywhere to explore accounting solutions designed for property management businesses.

Need professional accounting support? Contact Accountant Anywhere to discuss your bookkeeping, reconciliation, and financial reporting requirements.

How CPA Firms Can Scale with White-Label Accounting Services

Certified Public Accountant (CPA) firms face increasing pressure to manage growing client portfolios, meet reporting deadlines, maintain accounting accuracy, and deliver consistent service. As client demands increase, internal teams may struggle to balance routine bookkeeping, financial reporting, tax preparation, and higher-value advisory work.

Hiring additional employees can help, but recruitment, training, salaries, and employee retention require time and investment. For firms experiencing seasonal workload increases or steady client growth, expanding the internal team may not always be the most flexible solution.

This is where white-label accounting partnerships can help. They allow CPA firms to delegate selected accounting tasks to an external team while maintaining their own brand, client relationships, and review procedures.

With white label accounting services for CPA firms, businesses can increase their delivery capacity, manage workloads more effectively, and focus internal resources on client service and strategic growth.

In this guide, we explain how white-label accounting works, its key benefits, the services CPA firms can delegate, and the practical steps required to build a scalable accounting workflow.

What Are White-Label Accounting Services?

White-label accounting is a business arrangement in which an external accounting team completes agreed financial tasks that a CPA firm delivers to its clients under its own brand.

The external provider works according to the firm’s instructions, accounting procedures, software requirements, and reporting standards. The CPA firm generally retains control over the client relationship, final review, professional judgment, and client-facing communication.

Depending on the agreement, outsourced tasks may include bookkeeping, account reconciliation, accounts payable, accounts receivable, financial statement preparation, and tax-preparation support.

For example, a CPA firm managing 100 client accounts may find that monthly bookkeeping and reconciliation consume a significant portion of its employees’ time. An external team can help prepare the recurring accounting work, allowing the firm’s qualified professionals to review the results and focus on more complex client requirements.

The exact responsibilities must be defined in advance. Outsourcing preparation work does not automatically transfer professional obligations, approval authority, or regulatory responsibilities to the external provider.

Why CPA Firms Need Scalable Accounting Support

Growing an accounting practice requires more than attracting new clients. Firms must also ensure they have sufficient capacity to deliver accurate work within agreed deadlines.

Several challenges can make expansion difficult.

1. Increasing Client Workloads

As a CPA firm acquires more clients, the volume of transactions, financial records, reconciliations, and reporting requirements increases.

Without additional capacity or improved workflows, employees may struggle to complete recurring tasks on time. This can affect productivity and reduce the time available for client communication.

2. Rising Staffing Costs

Recruiting experienced accounting professionals involves salary expenses, training, onboarding, and ongoing employee management.

Smaller firms may find it difficult to maintain a large internal team when their workload changes throughout the year.

3. Seasonal Workload Fluctuations

Tax season and year-end reporting periods can create temporary increases in accounting workloads. A firm may need additional preparation capacity for several months without requiring the same level of staffing throughout the year.

4. Limited Time for Advisory Services

When experienced accountants spend most of their time on routine bookkeeping and data processing, they have fewer opportunities to focus on financial analysis, planning, and client relationships.

Delegating suitable preparation tasks can help firms make better use of their internal expertise.

How White-Label Accounting Helps CPA Firms Scale

White label accounting services for CPA firms can provide additional production capacity without requiring the firm to recruit every additional employee internally.

Here are several ways this approach can support business growth.

1. Increase Capacity Without Immediately Expanding Headcount

An external accounting team can handle agreed recurring tasks, helping firms manage additional client work when internal resources are limited.

For example, a CPA firm onboarding several small-business clients may assign routine bookkeeping and bank reconciliations to an external team. Its internal accountants can then review the work and address issues that require professional judgment.

The benefits depend on the provider’s capacity, service quality, and the firm’s ability to review completed work efficiently.

2. Improve Operational Efficiency

A clearly defined outsourcing workflow can help reduce repetitive tasks and improve the organization of accounting records.

When both teams follow consistent procedures, the firm can establish standard deadlines, documentation requirements, review checklists, and escalation processes.

This structure makes recurring work easier to manage as the client portfolio grows.

3. Manage Seasonal Demand

White-label partnerships can provide additional support during busy periods, depending on the provider’s availability and the agreed service arrangement.

CPA firms may use this support for bookkeeping backlogs, account reconciliations, workpaper preparation, and other defined tasks.

Planning capacity in advance helps firms avoid last-minute staffing pressure and establish realistic delivery schedules.

4. Focus on Higher-Value Client Services

Delegating routine preparation work can create more time for internal accountants to focus on activities such as financial analysis, business planning, and client advisory services.

However, the time saved depends on how effectively the firm manages the handoff, review, and communication processes.

5. Support Business Growth

With an appropriate delivery model, CPA firms may be able to accept additional clients without immediately expanding their internal team for every new engagement.

Before increasing the client portfolio, firms should confirm that their external provider has sufficient capacity and that internal reviewers can maintain quality standards.

Which Accounting Tasks Can CPA Firms Outsource?

The best tasks to outsource are generally repeatable, clearly defined, and supported by appropriate documentation.

Bookkeeping and Transaction Recording

External teams may record transactions, categorize expenses, maintain ledgers, and organize financial records according to the firm’s accounting procedures.

Consistent coding rules and documentation requirements help ensure that the work is ready for review.

Bank and Credit Card Reconciliation

Account reconciliation involves comparing accounting records with bank or credit card statements and identifying differences.

A preparation team can investigate unmatched transactions, document outstanding items, and prepare reconciliations for internal review.

Accounts Payable and Accounts Receivable

Depending on the agreed scope, outsourced staff may help record vendor invoices, maintain payment schedules, track customer balances, and prepare accounts receivable reports.

Payment approvals and other sensitive responsibilities should remain with the individuals authorized by the firm.

Financial Statement Preparation

External accountants may prepare draft financial statements, supporting schedules, and month-end reports for review.

The CPA firm’s reviewer should verify the figures, investigate unusual balances, and approve the final deliverables before they are provided to clients.

Tax-Preparation Support

Some providers offer tax-preparation assistance, including organizing source documents, preparing supporting schedules, and assembling draft returns.

Tax work requires particular care. Firms must confirm applicable confidentiality, disclosure, consent, licensing, and filing requirements before assigning these tasks. Final tax positions, professional review, signing, and filing responsibilities must be clearly allocated to appropriately authorized individuals.

How to Implement a White-Label Accounting Workflow

Successful outsourcing requires a structured process rather than simply transferring files to an external team.

Step 1: Identify Your Business Requirements

Start by reviewing the tasks consuming the most internal time. Identify recurring workloads, current bottlenecks, deadlines, and areas where additional support would be most useful.

Choose an initial scope that is manageable and easy to evaluate.

Step 2: Define Roles and Responsibilities

Establish who will prepare transactions, investigate discrepancies, review work, approve adjustments, and communicate with clients.

Document which activities the external team can perform independently and which require approval from the CPA firm.

Step 3: Establish Software and Access Requirements

Confirm which accounting platforms, document management systems, and communication tools will be used.

Provide access according to each person’s responsibilities. Use appropriate authentication, permissions, secure file-sharing processes, and procedures for removing access when it is no longer required.

Step 4: Create Standard Operating Procedures

Document the firm’s accounting methods, chart of accounts, reporting formats, deadlines, and review requirements.

Standard operating procedures help external staff understand how work should be completed and reduce inconsistencies between different client files.

Step 5: Start With a Pilot Project

Before transferring a large volume of work, test the arrangement with a limited number of client accounts or a defined accounting task.

Evaluate accuracy, turnaround time, communication, documentation quality, and the amount of internal review required.

Step 6: Monitor Quality and Expand Gradually

Track recurring issues, missing documents, correction requests, and reporting delays.

Once the initial workflow operates consistently, consider expanding the scope to additional clients or accounting tasks.

How to Choose the Right White-Label Accounting Partner

Choosing a suitable provider is essential for protecting client relationships and maintaining accounting quality.

Before entering an agreement, evaluate the following factors:

  • Relevant experience: Check the provider’s experience with your accounting tasks, client types, and software.
  • Service scope: Confirm which tasks are included and which remain the firm’s responsibility.
  • Quality control: Understand how work is reviewed before it reaches your internal team.
  • Communication: Establish response times, escalation procedures, and reporting schedules.
  • Data security: Review confidentiality agreements, access controls, data handling, and incident-response procedures.
  • Capacity: Confirm that the provider can manage your expected workload and accommodate future changes.
  • Pricing: Compare service fees with the total cost of internal review, corrections, software, and coordination.
  • Compliance: Determine the applicable professional and legal requirements, particularly when handling sensitive tax information or working across jurisdictions.

A strong partnership should support the firm’s processes rather than force the firm to change its entire operating model unnecessarily.

How Accountant Anywhere Can Support Accounting Firms

Accountant Anywhere provides outsourced accounting support for accounting firms, including bookkeeping, financial statement compilation, tax-return preparation support, payroll processing, and management accounting services, depending on the agreed scope.

Its accounting-firm services are designed to help businesses address staffing and operational capacity challenges while allowing their internal teams to focus on client service and growth.

If your firm is evaluating external accounting support, review the available services, software compatibility, delivery procedures, data-security arrangements, and review responsibilities before selecting a provider.

Frequently Asked Questions

1. What are white-label accounting services for CPA firms?

These services involve an external team completing agreed accounting tasks that a CPA firm delivers under its own brand. The CPA firm generally retains the client relationship, final review, and professional responsibilities assigned to it.

2. Can white-label accounting help a CPA firm serve more clients?

It can provide additional preparation capacity for recurring accounting tasks. The number of additional clients a firm can serve depends on transaction volume, provider capacity, internal review resources, and the complexity of each engagement.

3. Which accounting tasks are suitable for outsourcing?

Common options include bookkeeping, bank reconciliations, accounts payable, accounts receivable, financial statement preparation, and selected tax-preparation support. The appropriate scope depends on the firm’s needs and applicable requirements.

4. How can CPA firms maintain quality when outsourcing?

Firms can establish documented procedures, assign clear responsibilities, use review checklists, monitor turnaround times, and investigate recurring errors. A pilot project can help evaluate the provider before the arrangement expands.

5. Is white-label accounting suitable for small CPA firms?

It may be suitable for small firms that need additional accounting capacity but do not want to hire a full internal team. Firms should compare the total cost and management effort with the benefits of additional support.

6. What should a CPA firm check before outsourcing tax work?

The firm should verify the provider’s experience, confidentiality arrangements, data-security procedures, applicable disclosure and consent requirements, and the responsibilities for review, signing, and filing. Requirements vary depending on the type of work and relevant jurisdiction.

Conclusion

Scaling a CPA firm requires a balance between client acquisition, operational efficiency, accounting accuracy, and professional oversight.

White-label partnerships can help firms manage recurring workloads, improve capacity planning, and free internal professionals to focus on client relationships and higher-value services.

The most effective approach begins with a clearly defined scope, secure systems, documented procedures, and a reliable review process. Firms should test the workflow, measure its performance, and expand only when quality and turnaround meet their expectations.

By choosing the right partner and establishing clear responsibilities, white label accounting services for CPA firms can become a practical part of a long-term growth strategy.

Explore Accounting Support for Your Firm

If your accounting practice needs additional capacity, explore Accountant Anywhere’s accountants for accounting firms service page to learn more about its outsourced accounting support.

You can also visit Accountant Anywhere to explore its wider accounting services and solutions.

Ready to discuss your requirements? Contact Accountant Anywhere to arrange a conversation about your firm’s accounting workload, support requirements, and potential next steps.

Property Management Accounting Software: Yardi vs AppFolio Workflows

Property Management Accounting Software

Managing rental properties involves much more than collecting rent and handling tenant requests. Property management companies must also track income, process vendor invoices, reconcile bank accounts, monitor property expenses, and prepare accurate financial statements for property owners. As a portfolio grows, managing these activities manually can become time-consuming and increase the risk of accounting errors.

This is where property management technology becomes valuable. Accounting platforms help businesses organize financial transactions, maintain property-level records, and streamline recurring accounting tasks. Two widely used platforms in this industry are Yardi and AppFolio. Both support property management operations, but their workflows and suitability can differ depending on the type of properties managed, portfolio complexity, and business requirements.

Choosing the right property management accounting software requires understanding how each platform supports daily financial operations. Rather than comparing features alone, property managers should evaluate how rent collection, invoice approvals, bank reconciliation, and financial reporting fit into their existing processes.

In this guide, we compare Yardi and AppFolio workflows, explain their key differences, and discuss how property management companies can improve accounting efficiency.

What Is Property Management Accounting Software?

Property management accounting software helps businesses manage the financial activities associated with residential, commercial, and multifamily properties. Depending on the platform and configuration, it may connect accounting records with tenant information, leases, payment records, vendor invoices, and property reports.

Common accounting functions include:

  • Recording rental income and tenant payments
  • Tracking property operating expenses
  • Processing accounts payable and vendor invoices
  • Reconciling bank accounts
  • Maintaining general ledger records
  • Preparing financial statements and owner reports
  • Monitoring outstanding balances
  • Supporting month-end accounting procedures

By organizing these activities within a structured system, property managers can reduce repetitive data entry and improve visibility into property finances.

However, software alone does not guarantee accurate accounting. Businesses still need clear procedures, appropriate approvals, regular reconciliation, and qualified staff to review financial records.

Understanding Yardi Accounting Workflows

Yardi offers property management solutions designed for different property types and operational requirements. Its product options include solutions for residential, commercial, and larger real estate portfolios.

The exact workflow depends on the Yardi product, modules, configuration, and permissions used by the business.

1. Rent Collection and Accounts Receivable

Rent collection begins with maintaining accurate tenant, lease, and billing information. Once rent charges are established, the accounting workflow records payments and updates the corresponding tenant balances.

Property management teams can review outstanding balances, identify overdue payments, and monitor receivables through available reports.

For example, if a tenant has an outstanding balance of $2,000, the accounting team can investigate whether the amount relates to unpaid rent, additional charges, or a payment that has not been recorded correctly.

Keeping tenant ledgers accurate helps property managers monitor collections and prepare reliable financial reports.

2. Invoice Processing and Accounts Payable

Property managers regularly receive invoices for maintenance, utilities, cleaning, insurance, and other services.

A typical Yardi accounts payable workflow involves entering or importing an invoice, assigning it to the appropriate vendor and property, checking the expense category, and routing it for approval where configured.

Once approved, the invoice can proceed through the organization’s payment process.

For companies managing multiple properties, consistent coding and approval procedures help ensure that expenses are assigned to the correct property and recorded in the appropriate accounting period.

3. Bank Reconciliation

Bank reconciliation is an essential part of maintaining accurate financial records.

Accounting staff compare transactions recorded in Yardi with bank statement activity. They investigate missing transactions, duplicate entries, outstanding payments, and differences caused by timing.

For example, a payment may appear in the accounting system before it clears the bank. The reconciliation process helps identify whether the difference is a normal timing issue or requires further investigation.

Regular reconciliation supports more dependable cash balances and financial reporting.

4. Financial Reporting and Month-End Close

Yardi workflows can support property-level financial reporting and month-end accounting activities, depending on the solution and configuration.

Accounting teams may review income and expense reports, reconcile accounts, investigate unusual balances, record appropriate adjustments, and prepare financial statements.

A documented month-end process helps ensure that important tasks are completed consistently across properties.

Understanding AppFolio Accounting Workflows

AppFolio Property Manager combines property management functions with accounting tools. Its workflows can help property managers coordinate rent collection, expenses, vendor payments, and financial reporting within a connected platform.

The precise capabilities available depend on the product, subscription, configuration, and user permissions.

1. Rent Collection and Payment Tracking

AppFolio supports rental payment and accounting workflows that help property managers track tenant charges and payments.

When payments are processed and recorded, the corresponding financial records can be updated according to the configured workflow.

Property managers can use available reports to review balances, identify outstanding rent, and monitor collection activity.

Connecting payment information with tenant records helps reduce the need to maintain separate manual tracking systems.

2. Vendor Invoices and Expense Management

Property management companies must keep vendor expenses organized to maintain accurate property financials.

A typical invoice workflow includes receiving an invoice, checking vendor details, assigning the expense to the correct property, obtaining any required approval, and recording or processing the payment.

AppFolio offers accounting and vendor-management capabilities that can support these activities.

For example, when a maintenance company submits an invoice for repairs at a rental property, the accounting team should confirm that the work relates to the correct property, review the amount, and ensure that the expense is appropriately categorized.

Clear documentation and approval controls remain important even when parts of the workflow are automated.

3. Bank Reconciliation and Financial Review

AppFolio provides accounting functionality that supports financial tracking and account reconciliation.

Accounting staff should compare recorded transactions with bank activity, review unmatched items, and investigate differences before completing the reconciliation.

Automated matching can help reduce manual effort, but unusual transactions and unresolved discrepancies still require human review.

A consistent reconciliation schedule helps businesses maintain reliable financial records throughout the year.

4. Owner Statements and Financial Reports

Property owners need understandable reports showing how their properties are performing financially.

Depending on the configuration, AppFolio can support owner statements and property financial reporting that reflect rental income, expenses, and other relevant transactions.

Before distributing a statement, the accounting team should verify the underlying balances, review recorded expenses, and confirm that owner distributions agree with the available funds and applicable management agreements.

Accurate reports help property managers communicate financial performance more clearly.

Yardi vs AppFolio: Key Workflow Differences

Although both platforms support property management and accounting, their suitability depends on business requirements.

Portfolio Complexity

Yardi offers solutions for a broad range of real estate operations, including complex commercial and multifamily portfolios. It may be suitable for businesses requiring detailed accounting structures and workflows across multiple properties or entities.

AppFolio provides an integrated property management experience that can suit residential property managers and other operators whose needs align with its available product capabilities.

The best fit depends on the specific products being evaluated rather than the platform names alone.

Invoice and Payment Workflows

Both platforms can support accounts payable and payment-related processes, but the available automation and approval options depend on configuration.

Businesses should examine how invoices enter the system, how approvals are assigned, how payments are recorded, and how supporting documents are retained.

Financial Reporting

Both platforms support financial reporting, but report availability and customization may vary.

Before selecting a platform, identify the reports your business requires, including property-level income statements, balance sheets, rent rolls, accounts payable reports, and owner statements.

Confirm that the chosen solution can generate the required reports with an appropriate level of detail.

Ease of Use and Training

A system’s usefulness depends partly on how easily employees can learn and follow its workflows.

Property managers should evaluate the interface, training requirements, user permissions, and daily tasks performed by accounting staff.

A platform with extensive capabilities may require more configuration and training, while a simpler workflow may be sufficient for a business with less complex requirements.

Scalability

The right system should support the company’s current operations and anticipated growth.

Consider the number of properties, transaction volume, reporting requirements, number of users, and expected changes to the portfolio.

Businesses should also evaluate migration requirements and the effort involved in maintaining accurate data as operations expand.

How to Choose the Right Software for Your Property Management Business

Selecting property management accounting software requires a practical assessment of your accounting processes rather than relying on feature lists alone.

Consider these factors before making a decision:

Property portfolio: Identify whether you manage residential, multifamily, commercial, or mixed-use properties.

Accounting complexity: Determine whether your business needs multiple entities, specialized reporting, detailed approval procedures, or complex expense allocations.

Transaction volume: Evaluate how many rent payments, vendor invoices, and other transactions your team processes each month.

Reporting needs: List the financial statements and operational reports required by management and property owners.

Integration requirements: Check compatibility with your existing payment systems, document tools, and accounting processes.

Training and support: Assess implementation assistance, employee training, technical support, and ongoing system maintenance.

Total cost: Compare subscription or licensing costs, implementation, training, integrations, and the time required to manage the system.

A structured evaluation helps businesses select software that supports their actual workflow instead of paying for capabilities they may not need.

Best Practices for Improving Accounting Workflows

Regardless of the platform you choose, a consistent accounting process is essential.

  • Standardize expense categories: Use consistent coding rules across properties.
  • Establish approval procedures: Define who can approve invoices and authorize payments.
  • Reconcile accounts regularly: Review bank accounts and investigate discrepancies every month.
  • Review financial reports: Check unusual balances, outstanding liabilities, and property-level expenses.
  • Maintain supporting documentation: Keep invoices, receipts, payment confirmations, and adjustment records organized.
  • Control user access: Assign permissions according to employees’ responsibilities.
  • Document month-end procedures: Maintain a checklist to ensure recurring accounting tasks are completed.
  • Review automated transactions: Verify automated entries and matching results rather than assuming every transaction is correct.

These practices help property management companies maintain dependable records and reduce avoidable accounting problems.

How Accounting Support Can Improve Software Workflows

Implementing accounting software is only one part of building an efficient financial operation. Businesses also need trained personnel who understand property-level accounting, transaction review, reconciliation, and financial reporting.

An experienced accounting team can help maintain records, process invoices, review transactions, reconcile bank accounts, and prepare monthly financial reports.

Property management companies that lack sufficient internal capacity may consider outsourcing selected accounting activities. Before engaging an external provider, they should confirm the provider’s experience with the chosen platform, reporting responsibilities, security procedures, and review process.

Combining suitable technology with consistent accounting procedures can help businesses maintain accurate records while allowing property managers to focus on daily operations and portfolio growth.

Frequently Asked Questions

1. What is property management accounting software?

It is software that helps property management businesses record rental income, track expenses, manage financial transactions, reconcile accounts, and prepare financial reports.

2. Is Yardi better than AppFolio?

Neither platform is automatically better for every business. Yardi may suit businesses with complex commercial or multifamily requirements, while AppFolio may suit operators whose needs align with its integrated property management workflows. The right choice depends on portfolio complexity, features, cost, and reporting needs.

3. Can Yardi and AppFolio automate accounting tasks?

Both platforms support workflows that can reduce manual effort in areas such as payment tracking, accounts payable, and financial reporting. The specific automation available depends on the product, configuration, and subscription.

4. How often should property managers reconcile bank accounts?

Monthly reconciliation is a common practice. Businesses with higher transaction volumes or specific operational requirements may benefit from more frequent reviews.

5. Can accounting software eliminate bookkeeping errors?

Software can help reduce manual data entry and improve transaction tracking, but it cannot eliminate every error. Accurate records still require appropriate controls, supporting documentation, reconciliation, and human review.

6. What should businesses evaluate before choosing a platform?

Businesses should consider property types, portfolio size, accounting requirements, reporting capabilities, integrations, training, security, and total ownership costs.

Conclusion

Yardi and AppFolio can both support property management accounting, but the right choice depends on how well each platform fits your business’s financial workflows.

Yardi may be a strong candidate for operations requiring extensive property accounting structures and complex portfolio management. AppFolio may be suitable for businesses seeking connected property management and accounting processes within its available feature set.

Before choosing a platform, evaluate your existing workflows for rent collection, invoice processing, bank reconciliation, and financial reporting. Test important processes, confirm reporting requirements, and assess the time and resources needed for implementation.

Ultimately, effective property management accounting software should do more than record transactions. It should support accurate financial information, consistent accounting procedures, and informed business decisions as your property portfolio grows.

Looking to simplify your property accounting workflows? Explore our Property Management Accounting Services to learn how professional accounting support can help improve financial accuracy, streamline bookkeeping, and simplify property-level reporting.

In-House vs Outsourced Real Estate Bookkeeping: Cost and Benefits

In-House vs Outsourced Real Estate Bookkeeping

Managing real estate finances requires accurate bookkeeping, organized financial records, and regular reporting. Property management companies, real estate investors, and rental property owners must track rental income, operating expenses, vendor payments, maintenance costs, and owner distributions. As a real estate business grows, managing these financial responsibilities can become increasingly complex.

One important decision is whether to hire an in-house bookkeeper or work with an external accounting service. Both options offer advantages, but the right choice depends on the size of the property portfolio, transaction volume, available budget, and level of financial support required.

For many real estate businesses, outsourced real estate bookkeeping offers a flexible way to manage accounting tasks without maintaining a full-time bookkeeping department. However, in-house bookkeeping can also be beneficial for businesses that require daily financial oversight and direct access to accounting staff.

In this guide, we compare in-house and outsourced real estate bookkeeping, examine their costs and benefits, and explain how to choose the right approach for your business.

What Is In-House Real Estate Bookkeeping?

In-house real estate bookkeeping involves hiring an employee or maintaining an internal accounting team to manage financial records and transactions. The bookkeeper works directly for the business and generally follows its internal procedures, reporting structure, and accounting policies.

Typical responsibilities include recording rental income, tracking property expenses, reconciling bank accounts, processing vendor payments, maintaining financial records, and preparing regular reports.

An in-house bookkeeper may also coordinate with property managers, investors, vendors, and other employees to resolve accounting questions.

Benefits of In-House Bookkeeping

Direct communication: Employees can communicate with property managers and other team members throughout the working day. This can be useful when financial questions require immediate attention.

Greater operational familiarity: An internal bookkeeper can develop a detailed understanding of the company’s properties, management agreements, reporting preferences, and financial procedures.

Immediate access to records: Businesses may find it easier to discuss transactions and review financial information when the accounting employee is directly available.

Customized workflows: Internal teams can follow processes designed around the company’s specific requirements and adapt their work as operational needs change.

Challenges of In-House Bookkeeping

Despite these advantages, maintaining an internal bookkeeping function involves several responsibilities.

Businesses must account for salaries, employee benefits, recruitment, training, software subscriptions, and other employment-related expenses. Additional costs may arise when the company needs more than one accounting employee or requires specialized expertise.

An internal team may also struggle to manage increasing transaction volumes during busy periods. If the only bookkeeper takes leave or leaves the company, financial reporting and reconciliation tasks may be delayed.

For smaller real estate businesses, maintaining a dedicated employee can be expensive relative to the amount of bookkeeping work available.

What Is Outsourced Real Estate Bookkeeping?

Outsourced bookkeeping involves hiring an external service provider to manage some or all of a company’s bookkeeping responsibilities. Depending on the agreement, the provider may handle transaction recording, bank reconciliation, accounts payable, expense categorization, and monthly financial reporting.

Businesses can select services according to their requirements rather than hiring an employee for every accounting function.

With outsourced real estate bookkeeping, property management companies and real estate investors can access bookkeeping support while reducing the administrative responsibilities associated with managing an internal team.

The exact services, pricing structure, communication process, and reporting schedule depend on the provider and the scope of work.

Benefits of Outsourced Bookkeeping

Flexible service arrangements: Businesses can select support based on their accounting workload and operational needs. This flexibility can be helpful when managing multiple properties or expanding a portfolio.

Potential cost savings: Outsourcing may reduce the need to pay a full-time employee’s salary and employment-related expenses. The actual savings depend on service fees, transaction volume, and the amount of internal oversight required.

Access to specialized experience: An external provider with relevant real estate accounting experience may be familiar with rental income tracking, property-level expense reporting, bank reconciliation, and owner statements.

Scalable support: As the business grows, bookkeeping services may be adjusted to accommodate additional properties, transactions, and reporting requirements.

More time for core operations: Property managers and business owners can spend less time handling routine bookkeeping tasks and more time focusing on tenant relationships, property maintenance, acquisitions, and business development.

Challenges of Outsourced Bookkeeping

Outsourcing also requires careful planning. External providers may not be available immediately for every question, especially when communication schedules and response times are not clearly defined.

Businesses must also share relevant financial information with the provider, making data security, access controls, confidentiality, and documented procedures important considerations.

Additionally, outsourcing does not eliminate the need for management oversight. Business owners should review financial reports, approve appropriate transactions, and ensure that the provider’s work meets their requirements.

In-House vs. Outsourced Bookkeeping: Cost Comparison

Cost is one of the most important factors when choosing a bookkeeping arrangement. However, businesses should compare the total cost of each option rather than looking only at the monthly salary or service fee.

1. Employee Salaries and Service Fees

An in-house bookkeeper typically receives a salary, while an outsourced provider generally charges according to an agreed service package, transaction volume, hourly rate, or other pricing arrangement.

The best comparison considers the actual work required and the total cost of obtaining that support.

2. Recruitment and Training

Hiring an employee may involve recruitment expenses, onboarding time, training, and ongoing professional development.

An outsourced provider generally manages the recruitment and training of its own staff. However, the client may still need to invest time in explaining its accounting procedures, property structure, and reporting expectations.

3. Software and Technology

An internal accounting team may require bookkeeping software, property management systems, document storage, and other digital tools.

An external provider may use its own technology or work within the client’s existing systems. Businesses should clarify software licensing, integration requirements, and any additional technology charges before signing an agreement.

4. Capacity and Additional Support

As transaction volumes increase, an in-house team may need additional employees or overtime capacity.

An outsourced arrangement may offer access to additional resources, depending on the provider’s staffing model and contract. However, businesses should confirm how extra workloads affect service fees and turnaround times.

5. Cost of Errors and Delays

Incorrect entries, unreconciled accounts, and delayed financial reports can create additional work and make financial decisions more difficult.

Both internal and outsourced teams require appropriate review procedures. Businesses should assess the provider’s quality-control process, reconciliation schedule, reporting standards, and accountability for correcting errors.

The most cost-effective option is the one that delivers accurate, timely financial records at a sustainable total cost.

When Should You Choose In-House Bookkeeping?

In-house bookkeeping may be suitable for businesses that need frequent, direct accounting support and have enough ongoing work to justify an internal employee or team.

Consider an in-house arrangement if:

  • Your company processes a high volume of daily transactions.
  • Property managers regularly need immediate assistance with financial questions.
  • You have complex internal approval procedures.
  • You prefer employees to work directly within your office or operational team.
  • Your business has sufficient resources to manage recruitment, training, and employee costs.

Larger property management companies with established accounting departments may benefit from maintaining internal staff who work closely with finance leaders and operational teams.

When Should You Choose Outsourced Bookkeeping?

Outsourcing may be a practical option for businesses that want reliable bookkeeping support without building a large internal accounting department.

It may be suitable if:

  • You manage a growing portfolio of rental properties.
  • Your current team spends too much time on routine accounting tasks.
  • You need regular bank reconciliations and financial reports.
  • Hiring a full-time bookkeeper is not financially practical.
  • You want access to additional bookkeeping expertise.
  • Your business requires flexible support as transaction volumes change.

For companies evaluating outsourced real estate bookkeeping, it is important to select a provider that understands property-related transactions and can deliver clear, consistent reporting.

Before making a decision, ask about experience with real estate accounting, supported software, service-level expectations, data protection, pricing, and the process for resolving discrepancies.

Key Factors to Consider Before Making a Decision

The right bookkeeping model depends on more than the size of your business. Consider the following factors before choosing a solution.

Property portfolio size: Businesses managing several properties may have different needs from companies overseeing hundreds of units.

Transaction volume: Frequent rent payments, maintenance invoices, vendor transactions, and owner distributions can increase the bookkeeping workload.

Reporting requirements: Determine whether you need monthly financial statements, property-level reports, owner statements, or additional customized reporting.

Budget: Compare salaries, employment expenses, outsourced service fees, software costs, and management time.

Data security: Review confidentiality agreements, user permissions, secure document-sharing methods, and the provider’s procedures for handling financial information.

Communication and accountability: Establish who will answer questions, approve transactions, review reports, and resolve accounting discrepancies.

Growth plans: Choose an arrangement that can accommodate future changes without creating unnecessary costs or operational disruption.

Can You Combine In-House and Outsourced Bookkeeping?

Yes. Some real estate businesses use a hybrid bookkeeping model that combines internal oversight with external accounting support.

For example, an internal property manager or finance employee may approve expenses, coordinate with vendors, and review reports, while an external bookkeeping team handles transaction entries, bank reconciliations, and monthly reporting.

This approach can provide operational control while reducing the amount of routine accounting work handled internally.

However, a hybrid arrangement works best when responsibilities are clearly defined. Businesses should establish who records transactions, who approves payments, who reconciles accounts, and who reviews the final financial statements.

Clear procedures help prevent duplicate work, missed transactions, and confusion over accountability.

How to Choose the Right Bookkeeping Partner

If you decide to outsource, selecting the right provider is essential for maintaining accurate financial records.

Look for a provider with relevant real estate bookkeeping experience and a clear understanding of rental income, property expenses, bank reconciliation, and financial reporting.

Ask potential providers about their onboarding process, supported accounting platforms, turnaround times, reporting frequency, security measures, and quality-control procedures.

It is also useful to understand how they handle missing documents, unreconciled transactions, unexpected expenses, and corrections to previously recorded entries.

Review the service agreement carefully to confirm which tasks are included, which services cost extra, and what responsibilities remain with your company.

A dependable bookkeeping partner should provide consistent records, transparent communication, and reports that support informed business decisions.

Frequently Asked Questions

1. Is outsourced real estate bookkeeping cheaper than hiring an in-house bookkeeper?

It can be, particularly for small and medium-sized businesses that do not require a full-time bookkeeping employee. However, the cost difference depends on transaction volume, service scope, employee expenses, software requirements, and the level of support needed.

2. What services are included in real estate bookkeeping?

Services may include recording rental income, categorizing expenses, reconciling bank accounts, processing accounts payable, maintaining property-level records, and preparing monthly financial reports. The exact services depend on the provider and agreement.

3. Is outsourced bookkeeping suitable for small property management companies?

Yes. Outsourcing may help smaller companies maintain organized financial records without hiring a full-time accounting employee. It is important to choose a service package that matches the company’s transaction volume and reporting needs.

4. Can I keep control of my financial records when outsourcing?

Yes. Businesses can retain ownership and appropriate access to their accounting systems while assigning specific bookkeeping responsibilities to an external provider. Clear access permissions, approval procedures, and reporting arrangements help maintain control.

5. How do I decide between in-house and outsourced bookkeeping?

Compare your budget, transaction volume, property portfolio, reporting needs, and preferred level of direct oversight. An in-house team may suit businesses requiring frequent internal support, while outsourcing may suit companies seeking flexible accounting assistance.

6. Can outsourced bookkeeping support business growth?

It can help businesses manage increasing bookkeeping workloads without immediately expanding their internal accounting team. The effectiveness of this approach depends on the provider’s capacity, service quality, technology, and ability to meet changing requirements.

Conclusion

Choosing between in-house and outsourced real estate bookkeeping requires a careful evaluation of cost, operational control, workload, and long-term business goals.

In-house bookkeeping offers direct communication, familiarity with internal processes, and immediate access to accounting staff. However, it also involves employee costs, recruitment, training, and responsibility for maintaining the required accounting capacity.

Outsourcing can provide flexible support, access to specialized experience, and the opportunity to reduce routine administrative work. For growing real estate businesses, it may offer a practical way to maintain accurate financial records without building a large internal accounting department.

Ultimately, the right choice depends on your business’s individual requirements. By comparing total costs, reviewing service quality, and establishing clear accounting procedures, you can choose a bookkeeping arrangement that supports accurate reporting and sustainable growth.

For businesses considering outsourced real estate bookkeeping, the priority should be finding a solution that delivers reliable financial records, transparent reporting, and consistent support as the property portfolio expands.

Visit Accountant Anywhere to explore professional property management accounting and bookkeeping services tailored to your business needs.